Tag Archives: Statistics Canada

Cracks In Future For Canada Retirement Income

“Warning signs include declining private-sector pension coverage and the gradual erosion of Old Age Security’s income-replacement role, as benefits indexed to inflation fall behind wage growth.” C. D. Howe Institute
  • Canada’s retirement income system has generally served seniors well. Average income replacement rates remain high, poverty among seniors is low, and seniors’ median net worth has more than doubled in real terms since 1999.
  • But cracks are emerging. Public and private pensions now replace 10 percentage points less of pre-retirement income than two decades ago, low replacement rates are becoming more common among lower-middle earners, private-sector pension coverage is declining, and OAS is steadily losing ground as a source of income replacement.
  • The authors argue that Canada should rethink how the system delivers income replacement and poverty protection. They propose exploring a targeted “Canadian seniors benefit” combining OAS and GIS, shifting OAS’s income-replacement role to an expanded CPP/QPP, and strengthening employer-based retirement savings for workers without workplace pensions.

The authors wish to thank Xavier Dufour-Simard and Francois Laliberté-Auger for their assistance in carrying out some of the analyses contained in this paper. The authors also extend their gratitude to Sebastien Betermier, Colin Busby, David Dodge, Malcolm Hamilton, Sarah Hobbs, Abid Kazmi, Sébastien LaRochelle-Côté, Alexandre Laurin, Bernard Morency, James Pierlot, William B.P. Robson, Allan Shapira, Richard Shillington, John Stapleton, Michael Veall, and several anonymous referees for valuable comments and suggestions. The analyses contained in this paper were carried out at the Quebec Inter-university Centre for Social Statistics (QICSS), a member of the Canadian Research Data Centre Network (CRDCN). The activities of QICSS are made possible by the financial support of the Social Sciences and Humanities Research Council (SSHRC), the Canadian Institutes of Health Research (CIHR), the Canada Foundation for Innovation (CFI), Statistics Canada, the Fonds de recherche du Québec and all the Quebec universities that contribute to their funding. Conclusions, interpretations, and possible errors remain our own.

Introduction

Over the past decade, there has been little investigation into how seniors are faring with respect to the retirement system’s two key objectives: helping individuals sustain their standard of living in retirement (income replacement) and protecting them from financial hardship at older ages (poverty alleviation).

This stands in contrast to the rich policy discussion that led to the 2016 federal-provincial agreement to enhance the Canada (and Quebec) Pension Plan (CPP/QPP). Discussions focused on several major developments. The arrival of the first cohorts with full CPP/QPP earnings histories had helped lower poverty among seniors (Milligan 2008). Increased generosity in the Guaranteed Income Supplement (GIS) and CPP/QPP also contributed significantly to declining poverty rates (Schirle 2013). As Veall (2008) argued, the retirement income system was largely accomplishing its poverty alleviation objective. On income replacement, the debate leading to CPP/QPP enhancement made clear that overall rates were high in the population (LaRochelle-Côté et al. 2008; Ostrovsky and Schellenberg 2009). However, mid-earners without employer pension coverage were most at risk because public pensions offer relatively low replacement rates for them1Throughout, “public pensions” refers to the first two pillars of the system – OAS/GIS and CPP/QPP – and not to employer pension plans for public-sector workers, which belong, like private-sector plans, to the third pillar. (Ostrovsky and Schellenberg 2010). That extensive discussion took place less than two decades after another successful CPP/QPP reform took effect in 1998 (Little 2008).
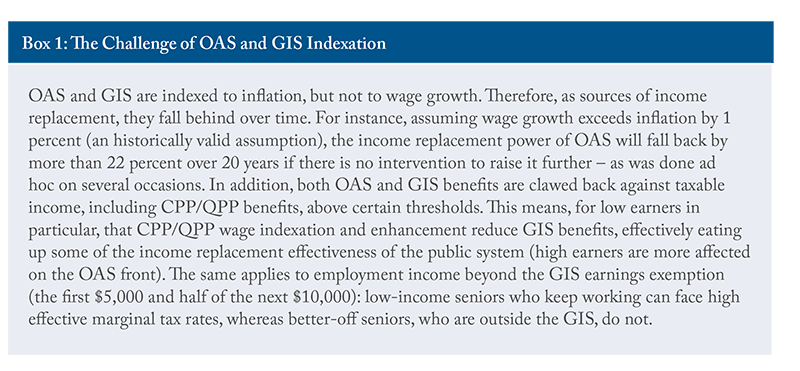
Since the discussions leading to the 2016 agreement, much has occurred, including a pandemic, a surge in inflation, and significant financial market fluctuations. Although the CPP/QPP multi-decade expansion has been rolling out effectively, retirees have faced setbacks elsewhere. The continuing decline in defined benefit (DB) plan coverage in the private sector has turned off the “automatic pilot” for many workers’ retirement savings. Meanwhile, Old Age Security (OAS) and the GIS continue to protect against poverty despite the recent inflation surge because they are indexed to prices. But they are losing ground as sources of income replacement. Unlike CPP/QPP, whose benefits at retirement reflect wage growth over a worker’s career, OAS and GIS amounts are only indexed to prices and fall behind wage growth (see Box 1). Future retirees who rely heavily on OAS/GIS will therefore see lower replacement rates than today’s retirees. These trends suggest that Canada’s retirement income system risks falling behind.

Because of the importance of the retirement income system and the growing size of the senior population, public claims abound that seniors cannot make ends meet, live in poverty, or struggle with the cost of living. These sentiments are often behind proposals to further expand pension coverage and to increase benefits for older Canadians, such as OAS. There are also those advocating the opposite; namely, that retired babyboomers fare much better than prior generations of retirees and that, as a result, OAS should be curtailed for higher-income earners and left to play only a poverty alleviation role, potentially freeing up financial resources for other uses.

This Commentary, drawing heavily on Boisclair et al. (2025a), has two aims.

  • First, it investigates the financial outcomes of seniors over two decades (2002 to 2022), comparing their retirement incomes to prior earnings and taking a look at household balance sheet data. It finds that seniors have, on average, fared rather well financially, both in terms of flows (income/consumption) and of stocks (net wealth).
  • Second, the paper illustrates and acknowledges the changes in income composition and income replacement at older ages in recent decades – in particular, decreasing private sector pension coverage and a retreating role of the first pillar (OAS/GIS) of the retirement income system. It then discusses some options to reform the system and refocus it on its objectives.

Data Sources to Assess Seniors’ Financial Situation

To evaluate whether the retirement income system met its objectives in the past 20 years, we mainly rely on Statistics Canada’s Longitudinal Administrative Databank (LAD). The LAD offers detailed financial information derived from the tax records of 20 percent of the Canadian population. It allows us to obtain precise income measures at multiple points over a taxpayer’s lifetime and provides information on household composition. As a complement, we use Statistics Canada’s Survey of Financial Security for balance-sheet analysis. Both datasets are subject to substantial lags: LAD data are available through 2022 and SFS data through 2023. Readers should keep these lags in mind when interpreting our findings.

When inflation peaked in 2022, interest rates rose sharply, and housing prices fell from their peak in some major markets, while financial markets rose strongly. Because public pensions are indexed to prices, seniors’ income from OAS, GIS, and CPP/QPP was largely protected; financial and pension assets have generally grown; housing wealth, by contrast, may be somewhat overstated for owners in the most affected markets.

Poverty alleviation: With respect to poverty alleviation, we use key measures of poverty that can be constructed with tax data. As is clear from the literature, there is no single perfect measure of poverty (Government of Canada 2018). We mainly use the low-income cut-offs, after tax (LICO-AT) measure, created by Statistics Canada. The LICO-AT has not been updated since 1992 and relies on meeting expenditures on housing, food, and clothing but does not account for the growing share of expenditures on transportation and communications (Noël 2017).2 But it is easily computable from LAD data.

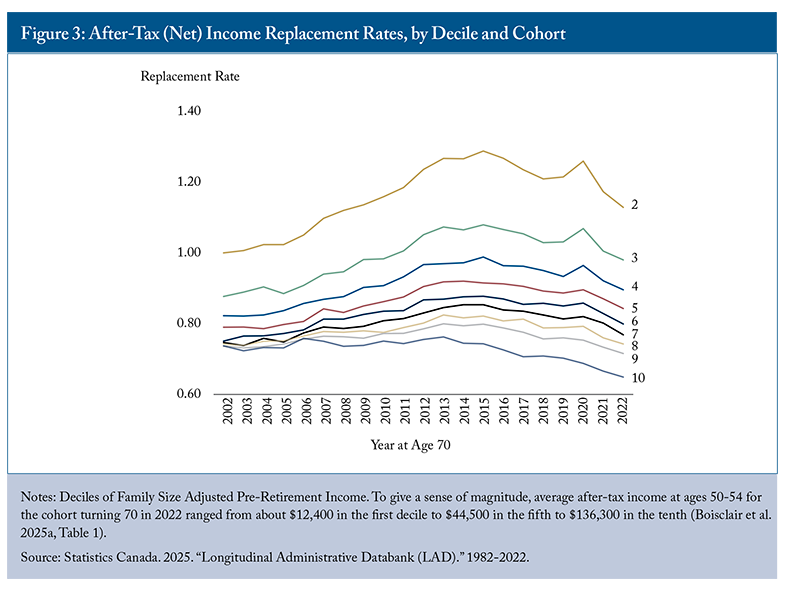
Income replacement: To evaluate the retirement income system in terms of income replacement, we calculate replacement with a measure of pre- and post-retirement income at some given ages. For this analysis, we define pre-retirement income as the average income in the age range 50 to 54, so as not to rely on a single year of income in the denominator of the replacement rate.3 We define the post-retirement window as the tax year in which the taxpayer turns 70.4
Income Replacement in Retirement

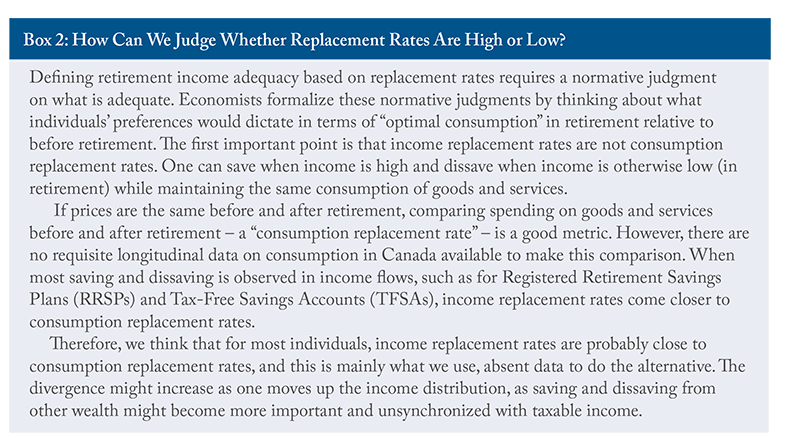
Family replacement rates (RR) on average are high, ranging from 80 percent to 90 percent (Figure 1).5 They increased by almost 10 percentage points (pp) between the 2002 and 2014 cohorts, before declining to roughly their levels at the beginning of the period. That hump-shaped pattern is mostly the result of changes in the denominator: pre-retirement earnings (at ages 50-54) declined slightly in real terms for cohorts turning 70 up to 2012, then rose by about 10 percent between the 2016 and 2022 cohorts (Boisclair et al. 2025a).
Retirement incomes, by contrast, increased steadily over the period. Including TFSA net withdrawals as income increases the RR by only 2 to 3 percentage points, with little effect on replacement rates, although this could change as TFSA use increases. Replacement rates are higher on an after-tax basis, since tax rates are lower at older ages due to several tax measures and to the progressivity of the income tax schedule.6

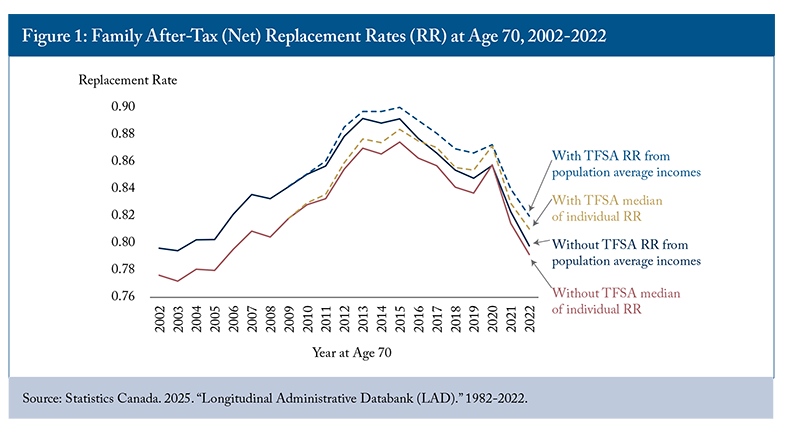
Figure 2 shows that despite similar gross replacement rates, individual incomes at age 70 have changed composition over the past decades.7 Public pensions, defined as the sum of OAS/GIS and CPP/QPP, are a very important source of income for seniors on average, but the share of pre-retirement income they replace has been declining from 31 percent of total pre-retirement income in 2002 to 27 percent in 2022. We observe a similar declining trend for private pension income (27 percent to 21 percent).8 What may seem surprising is that private pension income is declining for these cohorts, but changes to Registered Retirement Income Funds (RRIFs) over time could explain at least part of this phenomenon. Overall, public and private pension incomes have gone down from representing 58 percent of pre-retirement income to 48 percent, a drop of 10 percentage points in less than 20 years. This is a large drop coming from the three pillars of the retirement income system.
If the contribution of these sources to replacement is falling, what is keeping gross replacement rates constant? A closer look reveals that gross replacement rates do not decline accordingly because of an increase in several other income sources, notably employment (+6 pp), dividend (+3 pp), and RRSP (+1 pp; excluding RRIFs and RRSP-purchased annuities) income. Employment income at 70 is not concentrated among the better off: relative to pre-retirement income, it contributes more to replacement in lower deciles (14 pp in the third decile versus 9 pp in the eighth in 2022), although it forms a larger share of retirement income in the top decile (Boisclair et al. 2025a, Table 3).9 We also observe a decline in investment income (-3 pp), which could reflect the growing importance of tax-favoured savings vehicles (RRSPs and TFSAs) over time. One can conclude that there is more diversity in income sources at age 70 than there was 20 years ago and that traditional retirement income, coming from public and private pensions, has eroded substantially as a percentage of pre-retirement income.
Income Replacement Across Income Groups

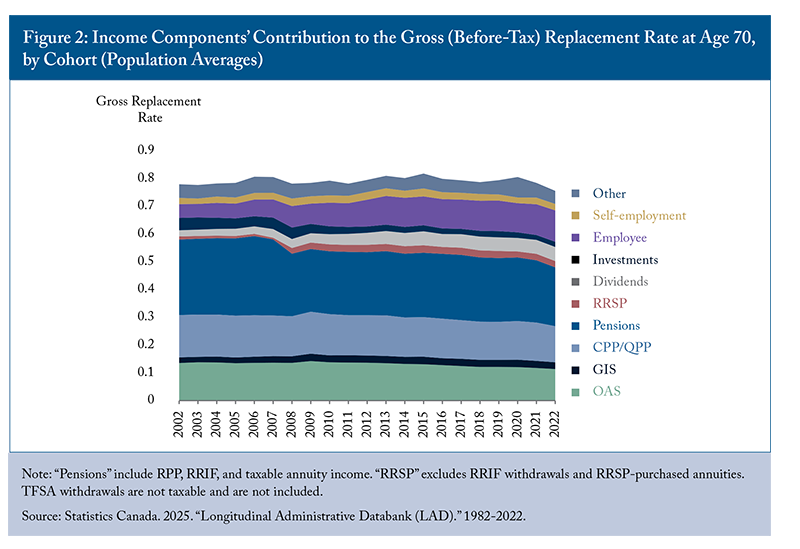
Replacement rates from public pensions decline as income rises, a well-known feature of Canada’s retirement income system. To examine how this relationship is evolving, we divide the income distribution into cohort-specific deciles of pre-retirement after-tax income and compute the RR for each decile over time. The RR for the first decile hovers around 2 and is omitted to enhance readability (Figure 3). This means that someone in the first decile sees their real after-tax income double at age 70 relative to ages 50-54. Replacement rates are thus very high at the bottom of the income distribution.
The RRs generally decrease as pre-retirement income increases. At the very top (10th decile), the replacement rate remains above 60 percent. Because saving and dissaving outside registered accounts matters more at higher incomes, income replacement rates are a less reliable guide to consumption replacement in the upper deciles, and relatively low rates there are not necessarily a sign of inadequacy. Most deciles increase until 2014 to 2016, followed by a decrease of a similar magnitude. Deciles 2 and 3 exhibit no net variation from 2002 to 2022, whereas higher deciles have positive net variations, ranging from 3 percentage points (decile 4) to 6 percentage points (decile 7) over the entire period. The only decile that sees a net negative variation is the 10th (highest earners), whose RR drops by almost 6 percentage points over the period. The decrease for this decile again reflects faster growth in pre-retirement income from 2016 onward, suggesting that this group is faring increasingly well before retirement and is therefore of less concern from a retirement-income policy perspective.

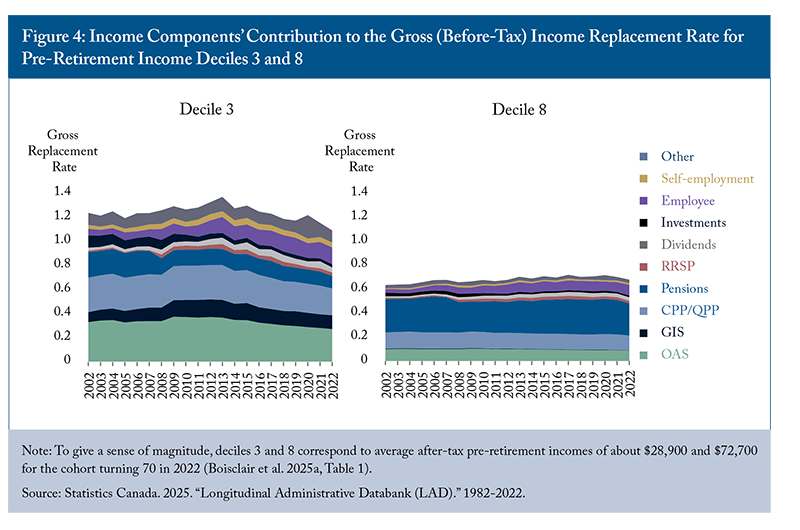
Figure 4 illustrates the difference in gross RR magnitude between the ends of the income distribution. The graph shows how lower deciles depend on public pensions (OAS, GIS, and CPP/QPP), which replaced almost 80 percent of their gross income in the early 2010s. On the other hand, the upper deciles rely a lot more on private pensions (including RRIFs). We observe in the decile 3 that public pensions have not followed the increase in pre-retirement income, resulting in a decreased contribution to the gross RR by more than 19 percentage points over the 2013-2022 period (from 80 percent to 61 percent). This trend is much less pronounced for the 8th decile, where the decline is 2 percentage points (23 percent to 21 percent) over the same period. This suggests that the deteriorating income replacement function of the public pension system is disproportionately affecting lower-income taxpayers. Overall, this leaves the bottom of the distribution most vulnerable to the erosion of public pensions and the top to the retreat of Registered Pension Plans (RPP).

Averages also mask dispersion within deciles. The share of taxpayers with replacement rates below 60 percent – a level that is hard to reconcile with standard consumption-smoothing preferences – rose by 7 to 13 percentage points across cohorts in deciles 3 to 5, and up to a third of seniors below the median have low replacement rates (Boisclair et al. 2025a). Earlier work with the same data shows that low replacement rates are concentrated among middle earners without employer pension coverage (Ostrovsky and Schellenberg 2010).

Poverty Protection in Retirement

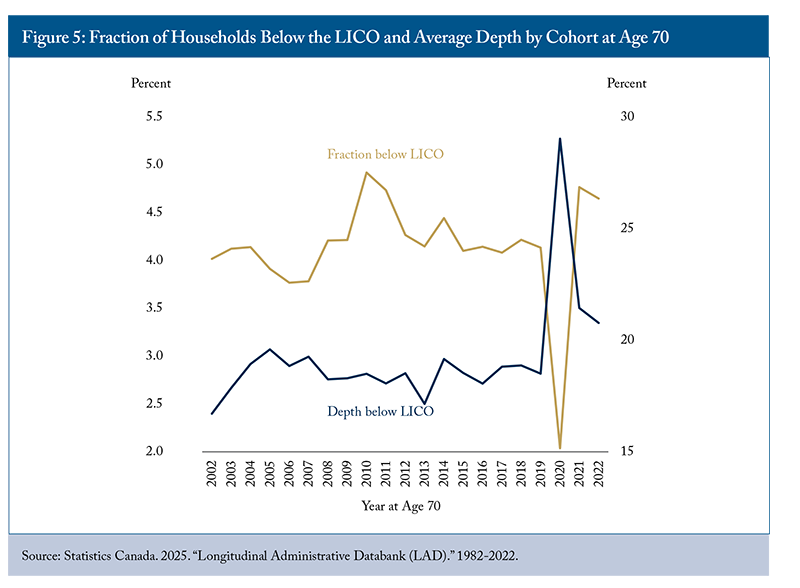
We find that the fraction of retired seniors below the LICO-AT is low (about 4 percent) and has remained very stable over cohorts, abstracting from the effect of the pandemic. The average depth, or shortfall, below the LICO over the period is also stable at around 18 percent (Figure 5). Thus, very few seniors fall below an absolute low-income threshold such as the LICO: Canada has been highly successful in protecting seniors from very low incomes. The same cannot be said for all Canadians, namely youth and working-age adults, however.

By comparison, in 2024, 5.4 percent of seniors lived below Canada’s official poverty line (the Market Basket Measure), compared with 11.5 percent of children and 12.6 percent of adults aged 18 to 64 (Statistics Canada, Table 11-10-0135-01). The dip in the low-income rate for 2020 is probably a reflection of larger transfers to households, such as the Canada Emergency Response Benefit (CERB). Overall, poverty rates are low among seniors because of the combined effect of OAS and GIS.10 In this light, it is notable that so much of the policy discussion revolves around poverty alleviation, when the erosion of the income replacement role of OAS is well underway and should be a cause for concern.

The Balance Sheet of Seniors

Income flows can be different from spending flows. When income flows include withdrawals from RRSPs and TFSAs, one also captures spending coming from the decumulation of these accounts (unless these monies are then transferred to taxable savings or to another investment use). This is therefore a good proxy, as argued above, but this will not include decumulation from other accounts and, more generally, consumption out of wealth. This can be important since a wealthy individual or household with a modest income may be better off financially, and spend more, than a counterpart with a high income but no wealth.
The most comprehensive source of data currently available on wealth holdings is Statistics Canada’s cross-sectional Survey of Financial Security (SFS).11 Since this is not longitudinal data, Table 1 shows cross-sectional statistics over time in constant 2023 dollars for households aged 65 and older. Specifically, the table reports both the proportion of households holding various types of assets and debts as well as the median value among households with positive balances. Median total assets and median net worth are also included and are calculated across all senior households, including those with zero or negative net worth. Conditional medians for individual assets cannot be added up to obtain the totals.
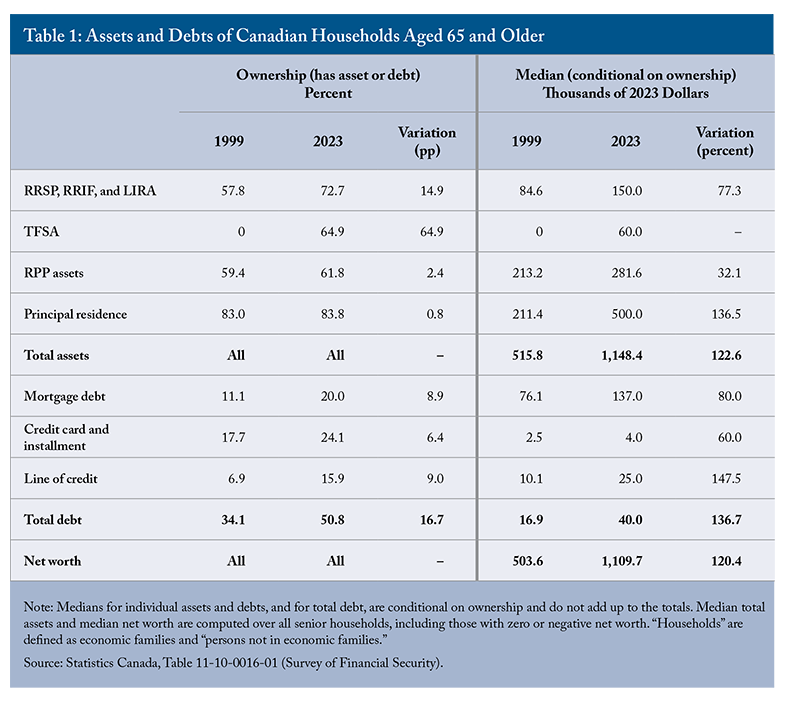
The median household net worth (assets minus debt) of those age 65+ has risen from $503,600 in 1999 to $1.1 million in 2023, or by 120 percent. This doubling over 24 years is a significant increase in the potential living standards of seniors. Of course, there is considerable dispersion, but the median senior household has a very high net worth. The share of seniors with RRSP assets rose from 57.8 percent to 72.7 percent, while the median value of those assets increased substantially, by more than 77 percent in real terms. TFSAs were introduced in 2009, and by 2023, 65 percent of households with at least one member aged 65 or older held TFSA assets, with a median value of $60,000. Importantly, while the share of households with RPP assets increased slightly over the period, the median value of those assets increased by 32 percent on average. Overall, traditional retirement savings, through pension plans and tax-favoured saving vehicles, increased substantially over time. Principal residences, held by 83 percent of senior households, also increased substantially in value: the median value among homeowners rose by 136 percent in constant dollars.12

Median debt increased as well by 136.7 percent over the period. But since debt is low relative to assets, its evolution does not significantly impact net worth. A few interesting changes occurred – for example, lines of credit, in particular home equity lines of credit, have more than doubled in prevalence and in median value – but traditional mortgage debt still accounted for the lion’s share of senior debt in 2023. Over the period, the share of households with mortgage debt nearly doubled to one in five (20 percent); households may have been able to borrow more on account of larger assets and rising income, but also lower interest rates (Bédard and Michaud 2021).

On average, seniors now have much higher net worth and financial equity, from which to finance consumption in retirement if they wish to do so. Even though counting home equity probably overstates the increase in net consumption opportunities coming from wealth, the overall portrait is quite positive for many in terms of non-government savings for retirement. However, this may not be available to some who have very few assets (Baldwin 2022). Notably, there is an important divide between homeowners and renters. The divide is stark: among families whose main earner was 55 to 64 in 2023, homeowners with an employer pension had a median net worth of $1.4 million, compared with $11,900 for renters without one (Statistics Canada 2024). Household type matters as well: seniors living alone, many of them widowed, had a median net worth of $475,900 in 2023, less than half that of senior families. Further complicating the interpretation of wealth differences is the increase in the average length of the retirement period, implying that one needs more financial wealth to sustain a given regular flow of consumption expenditures in retirement.

The Policy Challenges Ahead

To summarize the findings for policy, we must first note that the bottom income deciles rely on the public system (OAS, GIS, and CPP/QPP), while above the median, RPPs and other private retirement savings account for a much larger share. Hence, two issues warrant attention: 1) the future evolution of public pensions and its impact on the bottom deciles (and, perhaps less importantly, higher deciles due to CPP/QPP enhancement); and 2) the evolution of RPPs and other retirement savings arrangements and their impact on the replacement rates of individuals above the median. We discuss each in turn.

The Eroding Income-Replacement Role of OAS/GIS

With price indexation instead of wage indexation, the income replacement role of OAS/GIS has been slowly eroding, as indicated by Figure 2 – especially so for lower deciles, as shown in Figure 4. The 10 percent increase in OAS for those aged 75 and over introduced in 2022 partly offset this erosion for older seniors, but did not change the underlying indexation mechanism. And without further intervention, this will continue in the future, reducing OAS’s income replacement value by more than 22 percent over 20 years if real wage growth is 1 percent above inflation. The CPP/QPP expansion already underway will barely offset this decline in aggregate – roughly offsetting it for workers with earnings close to the Year’s Maximum Pensionable Earnings (YMPE), but not for lower earners, whose gains are smaller and partly clawed back through the GIS, while higher earners see a net gain (Boisclair et al. 2025a).

There are several possible options to adapt OAS, including a few known proposals. One would see OAS increase in generosity; another would see it curtailed; and a third would see it reshaped entirely. We review these proposals below as potential options or starting points for further policy discussions.

Option 1: Expand OAS for Those Aged 65-74

This idea was originally put forward in 2021 in a private member’s bill, Bill C-319, which died when the previous Parliament was dissolved. The content of the bill has moved to Bill C-261, which was first read in Parliament on February 9, 2026.13 A 2022 enhancement increased OAS by 10 percent for Canadians aged 75 and over; the current proposal would extend the same increase to Canadians aged 65-74.

We do not think this is the right approach for two reasons. First, an across-the-board increase is poorly targeted: poverty among seniors is now low relative to other age groups, and most of the cost would go to seniors who are not at risk of poverty. Second, it would not solve the underlying problem: a one-time increase restores some income replacement today, but with price indexation the erosion simply resumes, inviting further ad hoc increases. Relying on such raises on top of legislated inflation indexing leaves this important program – perhaps more than others due to its size and salience, as well as its single-government nature – at the mercy of political and public finance pressures.

Option 2: Start OAS Clawbacks at $100,000 of Family Income

A proposal from Generation Squeeze would cut OAS for better-off seniors – effectively lowering the clawback threshold by combining family incomes rather than treating them individually and/or increasing the rate compared to the current situation.14 Using the “family income” concept, contrary to individual income, which is currently the case for OAS clawback, would ensure that single or widowed individuals are not disadvantaged (the current 15 percent clawback starts at an individual income of $93,454 in 2025).

We share the premise of this proposal: any reform that refocuses OAS will, and should, ask more of better-off seniors. Our concern is rather with its design. While this would ease financial pressures on the program while protecting the poverty alleviation function for lower-income seniors, we believe this would come down to turning OAS into a “taxable GIS.” Indeed, the GIS’s very function is to ensure that seniors with little or no income other than OAS are lifted to just above some low-income threshold. It is unclear to us that duplicating this function is the best way forward. While a family-income test avoids disadvantaging single or widowed seniors, it would also end the individual character of OAS. Since its introduction as a universal benefit in 1952, OAS has provided lower-earning spouses – mostly women – with an independent source of income and could discourage couple formation later in life. Moreover, this proposal in itself is incomplete, as it does not address the erosion of income replacement above the median.

Option 3: Create a Canadian Seniors Benefit and Expand CPP/QPP

This proposal was made by one author of this paper in the Financial Post in late 2024 and in L’actualité.15 It would combine OAS and GIS – the OAS supplement – into a more streamlined “Canadian seniors benefit,” aimed solely at poverty alleviation, while only using CPP/QPP to achieve income replacement objectives. Canada has taken a similar approach elsewhere, for example with the Canada child benefit (CCB). This option has two distinct components: (a) replacing OAS and GIS with a targeted, federally funded “Canadian seniors benefit”; and (b) expanding CPP/QPP benefits, financed by higher contributions from workers and employers, to take over the income replacement function currently played by OAS. The two components fall under different jurisdictions – the first is federal, while the second requires federal-provincial agreement – but they are designed to go together: implementing the first without the second would amount to a cut in retirement income for middle-income workers.

More specifically, the idea consists in closing OAS as it currently exists, stripping it of its income replacement function – which has been in constant decline in recent and future decades – and moving its poverty alleviation function to an expanded GIS. The latter, which would become a targeted “Canadian seniors benefit,” would ensure that all seniors have an income at least equal to the low-income threshold. This is similar to what OAS and GIS currently accomplish together for lower-income seniors.

Consider an illustrative design for a single senior. The new benefit could guarantee the current combined maximum of OAS and GIS – about $22,800 a year in late 2026 – and be reduced by 40 cents for each dollar of other income. It would then be fully phased out at about $57,000 of other income between the current GIS cut-off ($23,112) and the OAS recovery threshold ($93,454). The reduction rate would thus be higher than the 15 percent OAS recovery tax but lower than the 50 percent to 75 percent GIS reduction rates, which would also improve work and saving incentives for low-income seniors. An earnings exemption similar to the current GIS one should also be preserved. Parameters for couples would need to be set separately. The first pillar would thus become a pure anti-poverty transfer program.

Such a redesign would have important distributional consequences, which hinge on a key difference between the two programs: OAS and GIS benefits depend on residence and current income, whereas CPP/QPP benefits depend on lifetime earnings. Keeping the new benefit tied to residence and current income is what protects seniors with low incomes, whatever their work history – including many with interrupted employment histories, caregivers, persons with disabilities, low lifetime earners, and immigrants with incomplete Canadian residence – since it would guarantee an income at least equal to the low-income threshold. By contrast, the income replacement function moved to CPP/QPP would accrue in proportion to lifetime earnings. Seniors whose current income places them above the range of the new benefit, but whose lifetime earnings were modest, would therefore lose OAS without an equivalent CPP/QPP gain. This is notably the case of lower-earning spouses in middle-income couples, often women, for whom OAS is currently an individual source of income; income testing on a family basis would remove it, unless the design preserves some individual entitlement.16

In any case, substantial savings would ensue for the federal government since OAS payments (excluding GIS) are planned to total nearly $68 billion in 2026/27. The actual size of the savings will depend on the specific parameter values for the redesigned “Canadian seniors benefit” and on the transition (see below), but would eventually amount to tens of billions of dollars a year. Then, a parallel increase in contributions would enhance CPP/QPP benefits to take over the income-replacement function of OAS. As a purely illustrative order of magnitude, replacing the maximum OAS pension for a worker with career earnings at the YMPE would require about 3 percentage points of additional contributions, split between employees and employers, on a fully funded basis.17This would effectively move the income replacement function of OAS “off-budget,” within a plan with strong governance, and bring it together with the rest of earnings-related income replacement in CPP/QPP. How this expansion is financed matters as much as its size. A fully funded expansion, like the one introduced in 2019, is fair across generations but takes about 40 years to mature, which, if OAS were closed at the same time, would leave middle-income workers retiring in the interim with neither OAS nor much additional CPP/QPP. A partially funded (pay-as-you-go) component would allow benefits to be paid sooner at the cost of transfers from future contributors.

Transition is the main challenge. Many workers have planned their retirement around OAS, and closing it abruptly would impose large and unforeseen losses on those who have already retired or are close to retirement – a retiree with $41,000 in income from a defined benefit pension and full CPP would lose about 15 percent of income – while a fully funded CPP/QPP enhancement would take decades to mature. The two must therefore move in step: OAS would remain in place for current retirees and cohorts close to retirement and be phased out gradually for younger cohorts as their CPP/QPP entitlements build up, with long advance notice. The CPP/QPP phase-in could also be accelerated, through two sources that can be combined: drawing on part of the assets accumulated in the base CPP and QPP and using part of the federal savings from closing OAS, for instance, to finance a partially pay-as-you-go component. Both involve transfers across generations to be weighed against the higher contributions they would imply later, and the latter would make federal savings correspondingly smaller in the short run. Beyond the transition, governments could decide whether to use the savings to lower taxes, reduce debt, or fund other priorities.

Clearly, such a major change would require careful and demanding coordination between the federal and provincial governments, at least with respect to the CPP/QPP part. Although such coordination is always a challenge in Canada, it is not unheard of. This is evidenced by the two important rounds of changes to CPP achieved in the past 30 years: in particular, the 1998 reform and the 2016 agreement to enhance the CPP; and by the contribution rate cuts announced in the federal Spring Economic Update.18 Cancelling those rate cuts could indeed be part of a broader remodelling under this option.

The Retreat of Private-Sector Pension Coverage

The landscape is changing rapidly for RPPs. Coverage in the private sector has eroded from an already low level, despite high hopes when Canada’s retirement system was established: 35 percent of private sector workers were covered in 1980, compared with fewer than one in four today (Boisclair et al. 2025a) – and only about 17 percent of core-age private-sector workers after correcting for double counting in official statistics (Dostie and Morris 2025). The quality of coverage has declined as well: in 1980, 90 percent of covered private-sector workers had a defined benefit plan, compared with 41 percent in 2023, so that fewer than one in 10 private-sector workers now has access to a DB pension (Boisclair et al. 2025a).19 As discussed, this is particularly concerning for above-median earners.

Although the primary goal of the CPP/QPP expansion currently underway was to cover workers without RPPs, this may translate into higher replacement rates for those with DB RPP coverage. Indeed, many public sector DB plans do have a so-called “integrated” structure with CPP/QPP20 – but it is too early to tell how many DB plans will have accounted for the CPP/QPP enhancement in the medium- to long-term.

However, middle- and higher-income earners without pension coverage have long been the group most at risk of inadequate income replacement. While solutions may exist to increase pension or retirement savings coverage for this target group, most are difficult or costly to implement or politically unpopular. For instance, a recent proposal in a C.D. Howe Institute Commentary (Ambachtsheer and Mazer 2026) suggests subsidizing small businesses to offer employee pensions. While this may help since cost is often a major concern for employers considering a pension plan, administrative burdens remain, and the subsidy could provide windfall gains to employers that would have offered a plan anyway. Furthermore, the very low take-up of Pooled Registered Pension Plans (PRPPs) illustrates that a stronger approach is required.

Quebec’s approach under its law on Voluntary Retirement Savings Plans (VRSPs), which requires employers to offer a basic savings plan with auto-enrolment, seems to be going in the right direction. Indeed, we have recently found that the law has resulted in increased savings in VRSPs but also in RRSPs and TFSAs (Boisclair et al. 2025b). However, enforcement is currently limited, and employer contributions remain voluntary, hampering more significant progress. Moreover, all workers are enrolled in the plans, even lower-income workers who might not benefit much or for whom an RRSP-type plan might even reduce future GIS benefits. In its most recent budget, the Quebec government has announced that it would study options to strengthen VRSPs, including a possible public VRSP managed by an independent organization, similar to the National Employment Savings Trust (NEST) in the UK.

If we are to address the income replacement gap for the target group, strengthening employer-based solutions will be needed to avoid an even larger CPP/QPP expansion than the one already underway and the one following the folding of OAS, based on option 3 above.

Conclusion

The evidence presented in this paper and elsewhere suggests that, on average, Canadian seniors have fared relatively well in recent decades and that the retirement income system has so far met its objectives in aggregate, both in overall income replacement and poverty protection. While some seniors continue to face hardship, this conclusion may surprise many and contrasts with the broader narrative of widespread financial difficulty among seniors.

Against this backdrop, the evidence also points to weaknesses that are already visible and likely to deepen:

  • public and private pensions now replace 10 percentage points less of pre-retirement income than they did two decades ago;
  • low income-replacement rates are becoming more frequent among lower-middle earners;
  • private-sector RPP coverage keeps declining; and
  • the income replacement function of OAS continues to erode and is not fully offset by the CPP/QPP expansion underway.

To date, other income sources – notably employment – have filled the gap, but they cannot be relied upon in the same way as pensions. One way forward, which we do not favour, would be to keep adjusting OAS on an ad hoc basis. Or Canada could, as we suggest, reshape OAS by folding its limited income replacement function into the CPP/QPP and merging the rest with GIS to create a “Canadian seniors benefit” that focuses solely on poverty reduction.

For income replacement above the median, private-sector RPPs and other employer-sponsored retirement savings arrangements could help bridge the growing gap, given their apparent value to workers (Dostie and Morris 2025). The enhanced CPP/QPP may also prove sufficient for this group following the current expansion and any changes that may come with the remodelling of OAS/GIS. If not, Canada could complement this approach with an “improved VRSP-like” system in which employers are encouraged or mandated to play a stronger role – as was always intended in the design of Canada’s retirement income system – or expand CPP/QPP even further still, this time above a certain level of earnings. In all scenarios, it is time to revisit Canada’s retirement income system.

For the Silo, Pierre-Carl Michaud and David Boisclair.

References

Ambachtsheer, K., and A. Mazer. 2026. Spreading the Benefits: A Targeted Tax Credit Is Needed to Expand Retirement Plan Coverage in Canada’s Private Sector. Commentary 704. Toronto: C.D. Howe Institute. https://cdhowe.org/publication/spreading-the-benefits-a-targeted-tax-credit-is-needed-to-expand-retirement-plan-coverage-in-canadas-private-sector/.

Baldwin, B. 2022. “The Evolving Wealth of Canadians: Who Is Better Fixed for Retirement? Who Is Not?” E-Brief. Toronto: C.D. Howe Institute. https://cdhowe.org/publication/evolving-wealth-canadians-who-better-fixed-retirement-who-not/.

Bédard, N., and P.-C. Michaud. 2021. “Playing with Fire? Household Debt near Retirement in Canada.” Canadian Public Policy / Analyse de politiques 47(1): 56–71. https://www.jstor.org/stable/27034142.

Boisclair, D., X. Dufour-Simard, and P.-C. Michaud. 2025a. “Retirement Incomes in Canada: Past, Present and Future.” Retirement and Savings Institute (RSI) Working Paper 19. September. https://ire.hec.ca/en/19-retirement-incomes-in-canada-past-present-and-future/.

______________. “La Loi RVER a-t-elle augmenté l’épargne des travailleurs au Québec?” Jacques-Parizeau Research Chair in Economic Policy Working Paper 5. October. https://cjp.hec.ca/en/5-la-loi-rver-a-t-elle-augmente-lepargne-des-travailleurs-au-quebec/.

Dostie, B., and T. Morris. 2025. “The Labour Market Impacts of Employer-Pension Plans.” Retirement and Savings Institute (RSI) Working Paper 18. August. https://ire.hec.ca/en/18-the-labour-market-impacts-of-employer-pension-plans/.

Financial Services Regulatory Authority of Ontario (FSRA). 2026. “Workplace Pension Membership Increases in Ontario, but Many Could Benefit from Additional Planning Steps.” News release. March. https://www.fsrao.ca/announcements/workplace-pension-membership-increases-ontario-many-could-benefit-additional-planning-steps.

Government of Canada. 2018. Canadian Poverty Reduction Strategy: What We Heard about Poverty So Far. Ottawa: Employment and Social Development Canada. https://www.canada.ca/en/employment-social-development/programs/poverty-reduction/reports/what-we-heard.html.

LaRochelle-Côté, S., J. Myles, and G. Picot. 2008. Income Security and Stability during Retirement in Canada. Analytical Studies Branch Research Paper Series 306. Statistics Canada.

Little, Bruce. 2008. Fixing the Future: How Canada’s Usually Fractious Governments Worked Together to Rescue the Canada Pension Plan. Toronto: University of Toronto Press. October.

Milligan, K. 2008. “The Evolution of Elderly Poverty in Canada.” Canadian Public Policy / Analyse de politiques 34(Supplement 1): S79–S94. https://doi.org/10.3138/CPP.34.4.S79.

Noël, Alain. 2017. “How Do We Measure Poverty?” Policy Options. November 9. https://policyoptions.irpp.org/2017/11/how-do-we-measure-poverty/.

Ostrovsky, Y., and G. Schellenberg. 2009. Pension Coverage, Retirement Status, and Earnings Replacement Rates among a Cohort of Canadian Seniors. Analytical Studies Branch Research Paper Series 321. Statistics Canada. https://www150.statcan.gc.ca/n1/en/catalogue/11F0019M2009321.

______________. 2010. A Note on Pension Coverage and Earnings Replacement Rates of Retired Men: A Closer Look at Distributions.

Schirle, T. 2013. “Senior Poverty in Canada: A Decomposition Analysis.” Canadian Public Policy / Analyse de politiques 39(4): 517–540. https://doi.org/10.3138/CPP.39.4.517.

Statistics Canada. 2024. “Survey of Financial Security, 2023.” The Daily. October 29. https://www150.statcan.gc.ca/n1/daily-quotidien/241029/dq241029a-eng.htm.

Veall, M. R. 2008. “Canadian Seniors and the Low Income Measure.” Canadian Public Policy / Analyse de politiques 34(Supplement 1): S47–S58. https://doi.org/10.3138/CPP.34.SUPPLEMENT.S47.

Wolfson, M. 2011. Projecting the Adequacy of Canadians’ Retirement Incomes. Institute for Research on Public Policy. https://irpp.org/research-studies/projecting-the-adequacy-of-canadians-retirement-incomes/.
Why Canadians Are Retiring Much Later

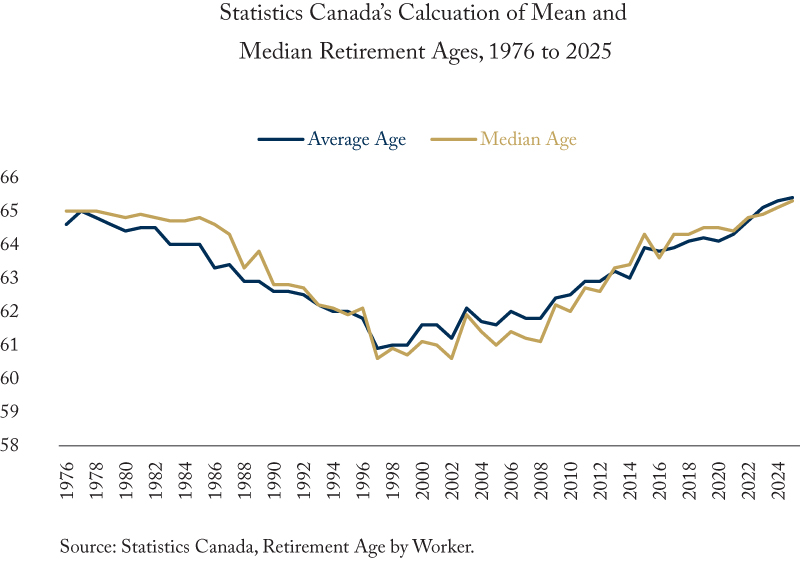
Statistics Canada’s retirement-age data tell a remarkable story.

After declining steadily from about age 65 in the late 1970s to roughly 61 around 2000, the average retirement age has climbed back to historically high levels (see Figure). 

In 2025, the average retirement age reached 65.4 years overall – 66.2 for men and 64.5 for women. 

The reversal reflects the interaction of several long-term forces affecting both the supply and demand for older workers. 

On the supply side, one of the most important structural changes has been the maturation of women’s participation in the labour market. Compared with earlier generations, today’s older women have much stronger lifetime attachment to paid work, higher pension entitlements, and retirement decisions that are increasingly coordinated with those of their spouses. This transformation has fundamentally reshaped aggregate retirement behaviour. 

Demographic trends reinforce this shift. Slower labour force growth resulting from population aging, lower fertility, and recent reductions in immigration have tightened labour supply. As fewer younger workers enter the labour market, employers increasingly rely on experienced older workers to fill skill shortages. 

Demand has evolved as well.

Canada’s economy has continued its transition toward service, professional and knowledge-based employment, where accumulated skills and experience often become more valuable with age and where many occupations are less physically demanding than in previous decades. 

Longer and healthier lives have also changed retirement behaviour. Many Canadians reaching their mid-sixties today can expect another two or three decades of life, much of it in good health. Retirement has increasingly become a gradual transition rather than a single event, with combinations of continued career employment, part-time work, consulting, self-employment and phased retirement becoming more common. 

Changes in social attitudes have contributed.

The elimination of mandatory retirement removed barriers for those wishing to remain employed, while employers and governments have become more attentive to age discrimination. Although the abolition of mandatory retirement appears to have had only a modest direct statistical effect on retirement ages, it expanded opportunities for those who wished to continue working. 

These developments have now reached an important milestone. Among Canadians aged 65 and over – the traditional age of public pension eligibility – the proportion continuing to work has grown steadily and is likely to continue increasing. 

This evolution suggests that Canada’s retirement income system deserves a fresh review. Much of its architecture was designed when retirement was relatively brief, labour force participation after age 65 was uncommon, and workplace pension coverage was both broader and more generous. 

The increase in retirement ages is therefore more than a demographic curiosity. It signals that Canadians have already adapted their behaviour to longer lives, changing labour markets and evolving retirement patterns. Public policy should now consider whether the retirement income system has adapted as well. 

Retirement is increasingly diverse. Some Canadians work longer because they choose to remain engaged; others because financial necessity leaves little alternative. 

At the same time, important features of the current system discourage continued work among lower-income seniors through Guaranteed Income Supplement earnings rules, while public pension benefits increasingly flow to many higher-income Canadians who remain economically active well beyond traditional retirement ages. 

For the Silo, John Stapleton/ Peter Hicks/ C.D. Howe Institute.

Peter Hicks is a policy adviser and a former Assistant Deputy Minister with Social Development Canada and John Stapleton is the new Social Policy, Ageing and Well-being Policy Fellow at the National Institute on Ageing. He is principal at his consultancy: Open Policy. 

Canada’s Top Twenty Percent Earners Are Saving More While Rest Sink Into More Debt

The K-Shaped Divide in Canadian Household Savings

Canadians going into more debt

The trend of Canadians going into more debt is a significant concern, driven by rising living costs and financial obligations such as mortgages, student loans, and consumer debt. Recent statistics reveal that total household debt in Canada surpassed $3 billion in September 2024, with the average Canadian now carrying approximately $41,500 in household debt, excluding mortgages. This trend has been steadily rising for years,

Money.ca
Debt to Income Ratio

This ratio reached 173.08% in 2021. Secured debt, such as mortgages or car loans, is a major contributor to household debt, while unsecured debt, including credit cards, relies on the borrower’s creditworthiness.

The cost of living is catching up to a large chunk of Canadians, with almost one in four taking on new debt in the last year. The Financial Consumer Agency of Canada found that more than half of Canadians are struggling to pay bills, and the OSB reported that 4.2 out of every 1,000 adult Canadians filed for insolvency in 2024, the highest rate since 2019. This accumulation of debt is attributed to spending consistently outstripping income for some time now.

Global News
To manage debt, Canadians are advised to consider debt consolidation, a debt management plan, or a consumer proposal. These options can help reduce the amount paid if the interest rates and terms of a consolidation loan from a bank are better than those of the individual creditors.

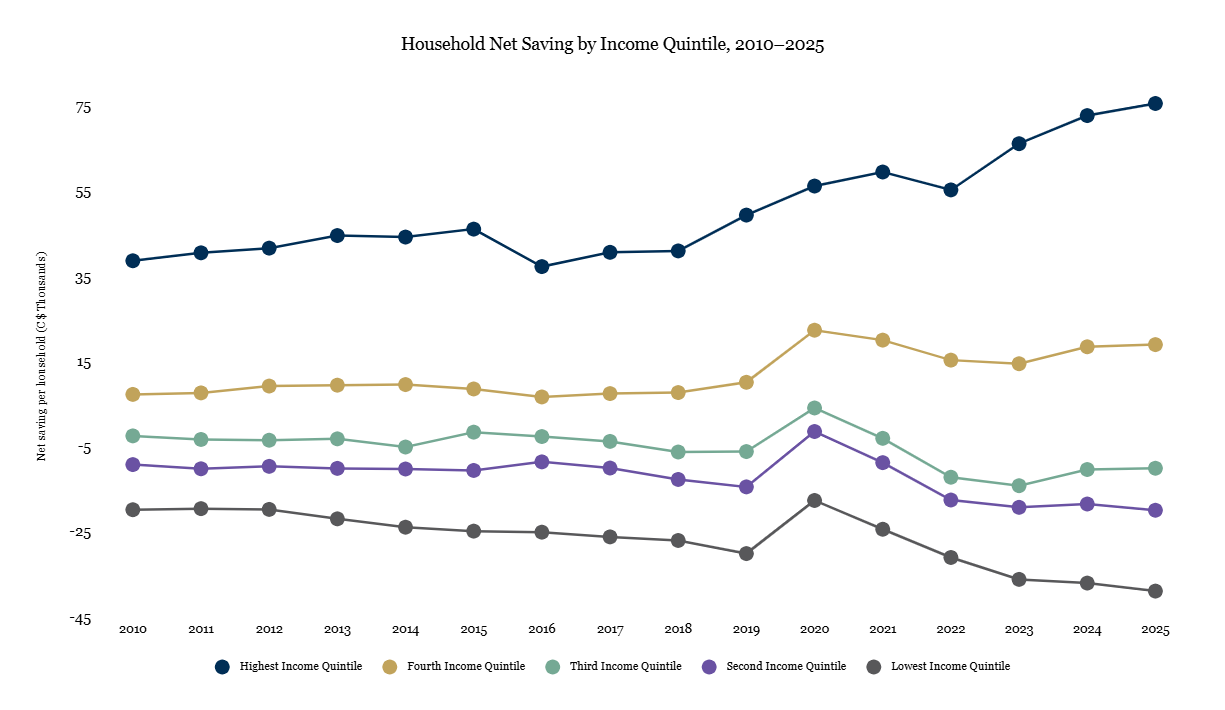
Canada’s household saving picture is splitting in two. Since 2021, the top fifth has lifted its average net saving to over $75,000 a year, while the lowest has sunk deeper into dissaving, spending nearly $39,000 more than its disposable income. The middle and second fifths have also slipped further into the red. Higher earners are pulling away as lower earners draw down savings and borrow to keep spending. For more on the health of Canada’s economy, see this C.D. Howe Institute memo.

Note: Negative values denote dissaving (consumption exceeds disposable income). Quintiles averaged the following income: Lowest quintile $33,000, second quintile $62,000, third quintile $88,000, fourth quintile $120,000, fifth quintile $219,000.

Source: Statistics Canada, Distributions of Household Economic Accounts (Table 36-10-0587-01). Figures are average net saving per household.

Canada Joins World’s Impending Population Crisis

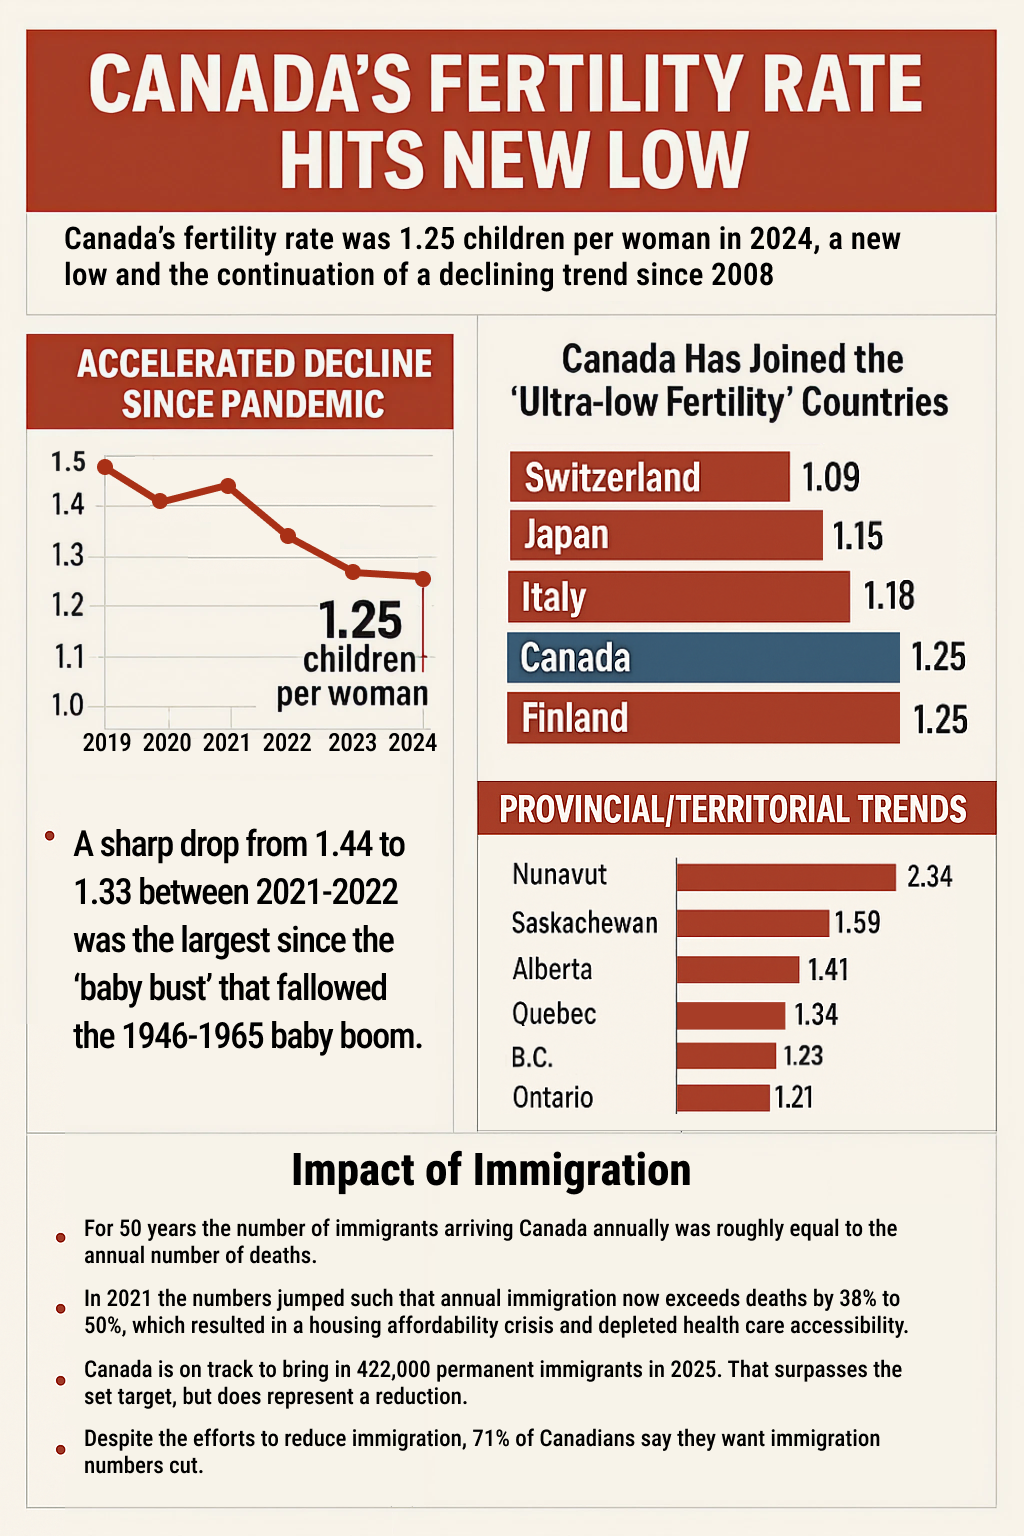
Canada’s fertility rate has just hit a record low.
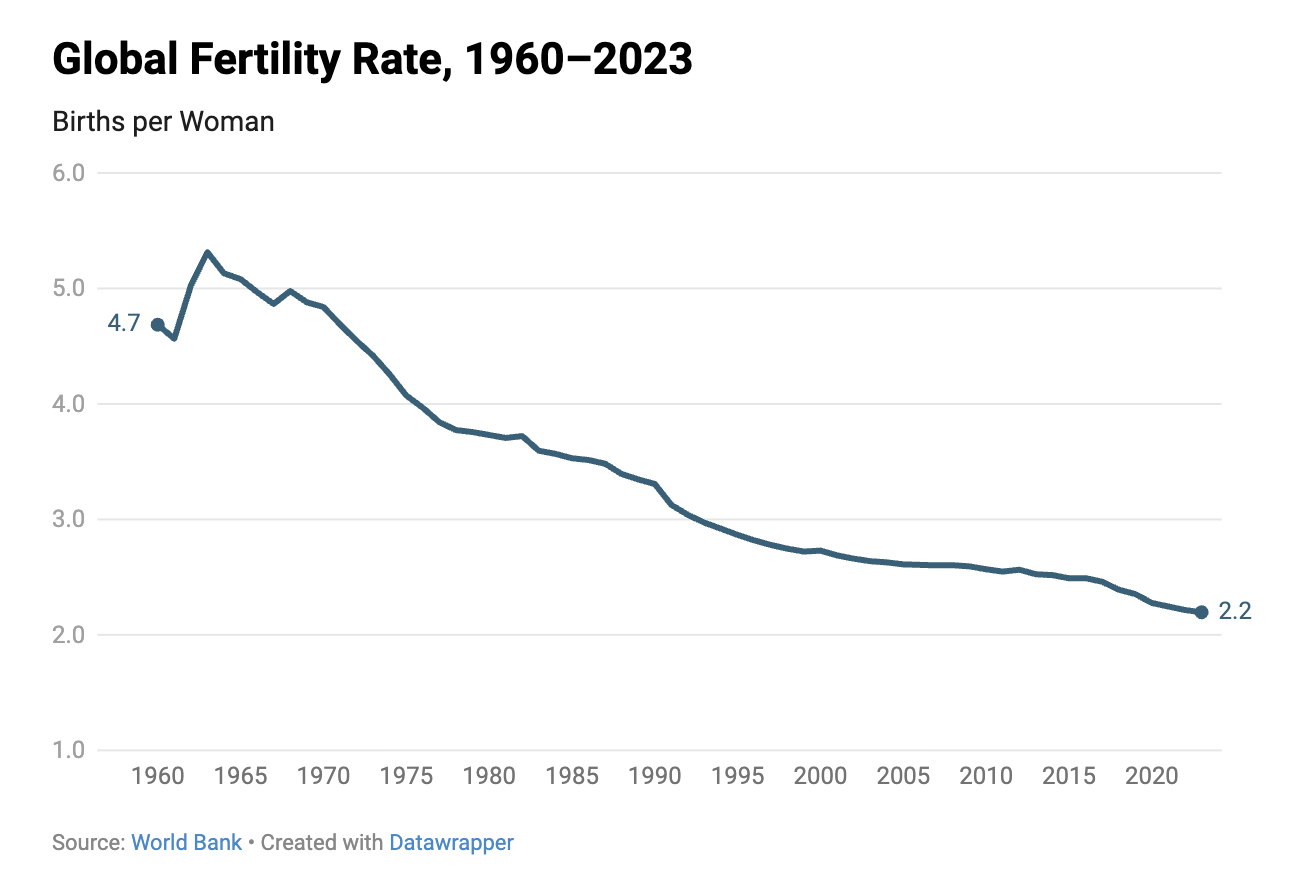
In case you missed it- the world is quietly entering a population crisis. Global fertility rates have plunged to their lowest level in 60 years, raising profound questions about how societies will sustain themselves in the decades ahead.
In Canada, births have fallen to just 1.25 children per woman, the lowest in our history. Behind the numbers are shifting values, economic pressures, and growing uncertainty about the future.
This week, let’s examine the global decline in birth rates and explore what’s driving it—and what it means for the economy, family, and national identity.
An Impending Population Crisis? World Fertility Rate Hits 60-Year Low
For the Silo, By Sylvia Xu / Epoch Times.

Fertility rates have plummeted worldwide over the past six decades, leading experts to warn of dire consequences as the downward trend continues.
Continued low fertility rates will cause “a gradual implosion of the world’s economy as the population ages and dies,” Steven Mosher, president of the Population Research Institute.
Mosher is an expert on population control, demography, and China.”
This will not occur overnight, of course, but once it is well underway, it will be difficult, if not impossible, to reverse course,” he said.
The fertility rate is the average number of children born to a woman in her lifetime; the birth rate is the number of live births per 1,000 people in a population over a given period.
Macroeconomist Jesús Fernández-Villaverde called low fertility rates “the true economic challenge of our time” in a February report for the American Enterprise Institute.
In 1960, the fertility rate was between four and five. By 2023, that number had halved to 2.2, approaching 2.1, the level at which a population replaces itself from one generation to the next.In July, the U.S. Census Bureau projected that the world’s population will reach 8.1 billion this year. Experts say that although the figure has grown from 3 billion in 1960, the number to watch is the pace of population growth.”
The rate of growth peaked decades ago in the 1960s and has been declining since and is projected to continue declining,” the Census Bureau stated.
Fernández-Villaverde warned that although the sagging rate of growth may not have immediate consequences, in less than 50 years, declining fertility will affect the world economy. Countries with low or negative birth rates will contend with a shrinking workforce and the ballooning costs associated with an aging population.
Global Fertility Rates
Only about 4 percent of the world’s population is in countries with high fertility rates—more than five children per woman—and all of those nations are in Africa, according to the Census Bureau. Even in those countries, fertility rates are generally lower than they once were.
The Census Bureau reported that nearly three-quarters of the world’s population is in countries where fertility rates are at or below the replacement level.
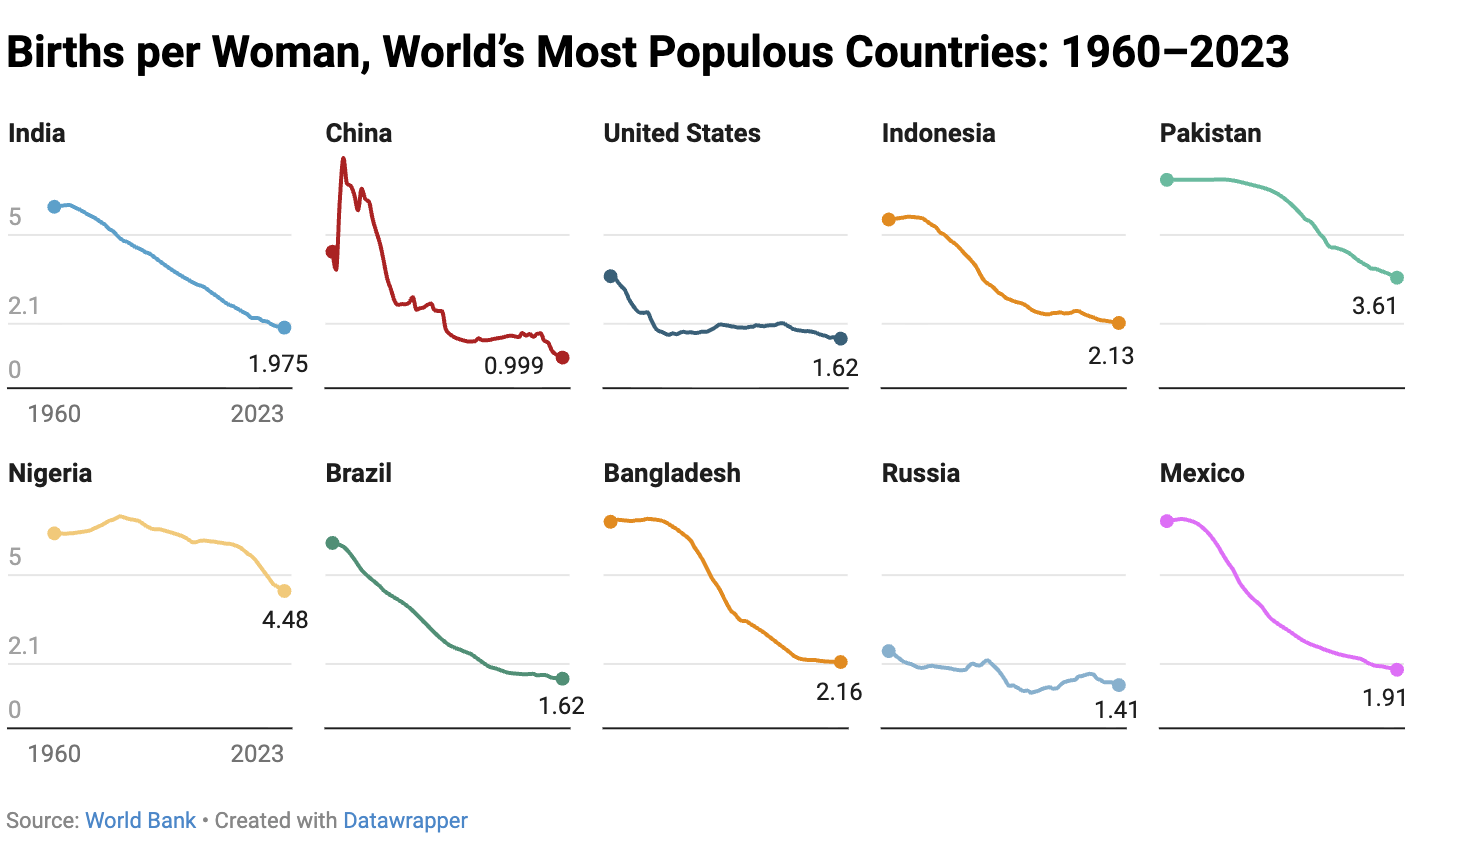
The fertility rate in India, the world’s most populous country, has steadily declined over the past six decades. In June, the U.N. Population Fund reported that India’s fertility rate stood at 1.9 children per woman, down from five or six children in 1960. In Canada, fertility rate fell to 1.25, well below the replacement level of approximately 2.1 children per woman needed to maintain a stable population.
In 1990, China’s fertility rate was 2.51, despite its one-child policy. By 2023, it had dropped to less than one birth per woman, according to the U.N.’s population division.In the United States, fertility has undergone a persistent decline. It fell below the replacement level in 1972, and in 2023, it reached 1.62—a historic low.Asian and European countries have the lowest fertility rates in the world, and South Korea (0.72), Singapore (0.97), Ukraine (0.977), and China (0.999) all have rates below one.  (Read More →)
Key Data & FactsSource: Statistics Canada

Forest Bathing Beats Stress Improves Immune System

Stress is ever present in current society, both personal stress and workplace stress contribute to the well documented link, between stress and chronic conditions. 

Data available from Statistic Canada’s – National Population Health Survey, demonstrates that personal stress is predictive of the development of a chronic health condition over the next four years (Statistics Canada, 2003).  The long term impact of these chronic health conditions can result in significant activity limitation from heart attack, diabetes, migraine, or arthritis or back problems.  Even more daunting is the higher predictive value of death for individuals suffering from cancer, bronchitis/emphysema, heart disease or diabetes.

Issaquah Forest Bathing (Shinrin Yoku) – What is it? – Issaquah Adventures

The practice of forest bathing itself is not a new concept.

Prior to the industrial revolution being “in nature” was part of everyday life.   The Japanese term Shinrin-yoku  meaning “taking in the forest atmosphere or forest bathing” was officially coined by the Japanese Ministry of Agriculture, Forestry, and Fisheries in 1982. (Park et al. 2010)

This novel practice of bathing in nature, demonstrates a wide variety of health benefits from which individuals in modern society can stand to gain.  With the increasing amount of individuals living in urban settings the exposure to nature is diminishing.

Field studies performed in Japan measured salivary cortisol levels (more commonly known as “stress hormone”) in university individuals.

The students were divided into two groups, one to spend a day in a forest setting, the other in a city setting.   Lower levels of stress hormone, as well as lower blood pressure and pulse rate was found in individuals in forest location. (Park et al. 2010)

Not feeling ready to take the plunge into full force bathing? Forest sitting and contemplation of bathing can calm you.

Further evidence has been documented  to demonstrate  the reduction of stress resulting from forest bathing, through the improvement of immune function via exposure to the natural environment.  Given that immune function is key in the prevention of chronic diseases this evidence is exciting.   Natural killer cells (as they are ingeniously named) are cells within the immune system which kill tumors or virus infected cells, through the release of enzymes which break down the cells.   In research studies natural killer cells have been found to be elevated for seven days after the forest bathing trip (Qing, 2010).  This seven day window of improved immune function is great news for the weekend warrior in all of us.

Many of us who live in North America are blessed with exposure to forest just outside our doorsteps.  This being said it doesn’t mean we always take advantage of it: between commuting to work, family and social commitments,  going from the house to the car may be the norm.  For the Silo, Ashley Beeton. 

References

Park, B.J., Tsunetsugu, Y., Kasetani, T., Kagawa, T., & Miyazaki, Y. (2010) The physiological effects of Shinrin-yoku (taking in the forest atmosphere or forest bathing): evidence from field experiments in 24 forests across Japan.  Environ Health Prev Med,  15,18–26.

Statistics Canada. (2003) Stress and Well-being (No 82-003). Retrieved from http://www5.statcan.gc.ca/access_acces/alternative_alternatif.action?l=eng&loc=http://www.statcan.gc.ca/pub/82-003-x/2000003/article/5626-eng.pdf&t=Stress%20and%20well-being

Qing, Li. (2010) Effect of forest bathing trips on human immune function.  Environ Health Prev Med, 15,9–17.

Make A Prairie And Say No To Land Without Life

image: www.ojibway.ca

So make a prairie…

It’s hard to believe it’s been almost fifteen years since I did some work recording for Statistics Canada. The job required door-to-door visits to all the homes in a designated area, interesting because I had a chance to see what people do in their yards. One residence in particular left a strong impression on me and it continues to resonate now in 2025 all these years later.

It was a beautiful home, probably 40 years old, on a fairly large estate.

The lawns were nicely manicured and the architectural evergreens were tastefully placed. It looked like a photo in a 1970’s Better Homes and Gardens.

This architectural sketch of a late 1970’s “Dream Green Home” at least shows a bit of “greenery” and a tree. image: public domain

But as I walked to the front door, I realized that there was no movement.

Nothing swayed in the afternoon breeze. There were no herbaceous plants, no flowers, and worse, no bees, no butterflies, no birds. This place had as little movement as my imaginary magazine photo. It struck me as being uninteresting and unnatural. Land without life.

In my experience we show ourselves at our best when we interact and connect with nature and even find a kind of fulfillment in it. This completion has been lost for many of us, but paradise can be regained at any time.

There are all kinds of small ways to re-connect and to bring restoration, not just to the land, but to ourselves as well. I encourage everyone to put in a garden of some kind. A vegetable garden is of course the most practical and immediately useful. Start small and easy if you have never had a garden before.

If the practicality of a vegetable garden isn’t appealing, then plant something in to nourish your soul.

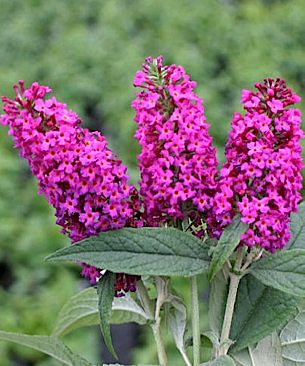
‘Miss Ruby’ Butterfly Bush-Buddleia image: www.green-living-made-easy.com
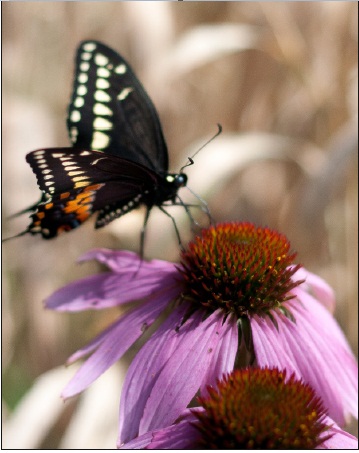
Rick’s home butterfly garden photo: M. Larmand

A couple of years ago I put in a no-maintenance garden specifically to attract hummingbirds. The thank-you’s come at dusk when increasing numbers of my little buddies do their end-of-day rounds. Scarlet runner beans, red monarda, salvia, tithonia, and crocosmia – they did the trick.

And copying the garden of a friend , I have also put in a small butterfly garden.

Milkweed, Echinacea, and butterfly bush (Buddleia) are good starter plants. I’m doing my small part to help save the monarch butterfly population. The nice thing about both these gardens is that they require almost no attention, just observation and enjoyment.

I’ve often thought about theme gardens. “There’s rosemary, that’s for remembrance…” Ophelia’s mad scene in Hamlet is a great starting point for a Shakespearean garden and a study of plant symbolism in literature. A biblical garden would also be an interesting exercise, though the plants themselves would be local approximations of Mediterranean species but the life lessons would be endless. Consider the lilies of the field. What about a cutting garden, a scented garden, a night garden?

Poets and painters have found inspiration in gardens. Like them, let nature take your breath away. Start small. To quote the American poet, Emily Dickinson:

To make a prairie it takes a clover and one bee.
One clover, and a bee.
And reverie.
The reverie alone will do,
If bees are few.

It doesn’t take much to make a prairie – or your own personal sanctuary.For the Silo, Rick Posavad.

Why Canadians Must Get More Sunlight

TORONTO – Following restrictive sun exposure advice in countries with low solar intensity like Canada might in fact be harmful to your health, says the co-author of a new study on sunlight and vitamin D.

VitaminD from Sun Exposure

The published study Sunlight and Vitamin D: Necessary for Public Health by Carole Baggerly and several academic researchers, examines how organizations such as World Health Organization’s International Agency for Research on Cancer and the U.S. Surgeon General call for sun avoidance, but ignore the fact that cutting out sunshine will reduce vitamin D, an essential vitamin for bone health, and create probable harm for the general population.

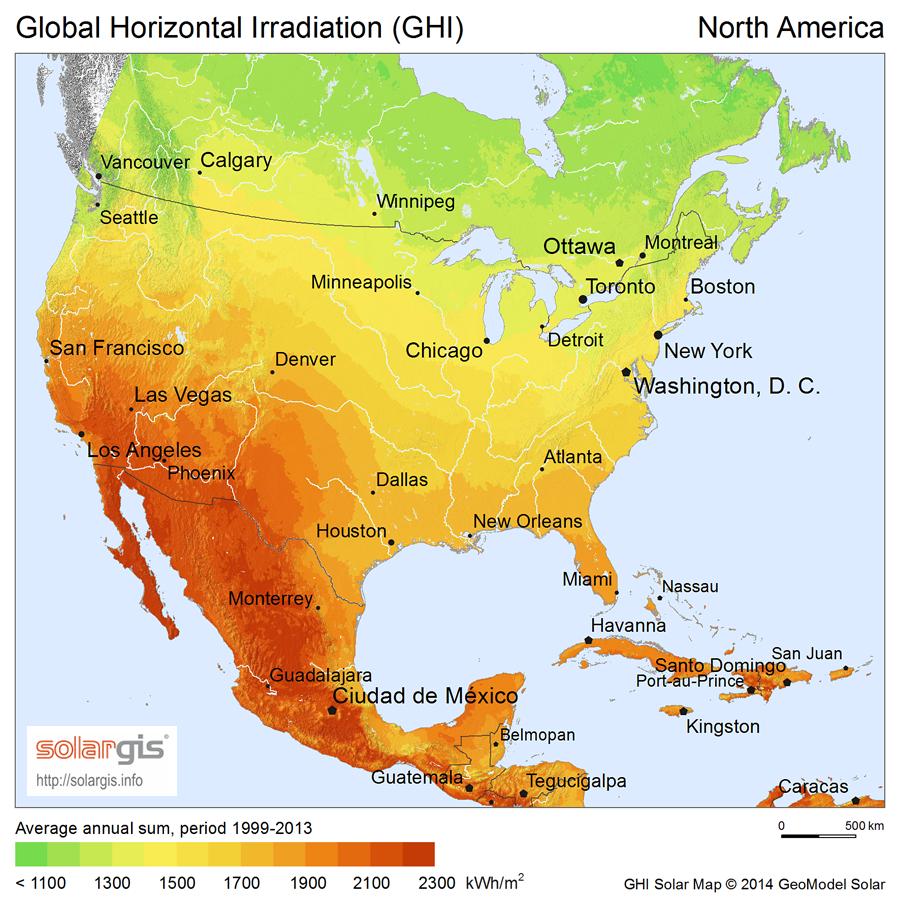
Canada sunshine map - Map of Canada sunshine (Northern America - Americas)

“Humans have adapted to sun exposure over many thousands of years and derive numerous physiological benefits from UV exposure, in addition to vitamin D,” said Baggerly, executive director of Grassroots Health and breast cancer survivor.

“These benefits are in addition to those derived from vitamin D alone and cannot be replaced by vitamin D supplements and therefore sun avoidance being recommended by the US Surgeon General, the Canadian Cancer Society, the Canadian Dermatology Association and others, is unnecessarily putting Canadians at risk.”

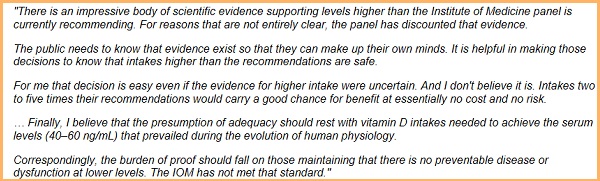
From mercola.com -studies suggest we need more sunlight than currently recommended dosages

Vitamin D is an essential vitamin that enables calcium absorption and is critical for good bone health. Low levels are linked to bone conditions such as rickets in children and osteomalacia and osteoporosis in adults.

In Canada, vitamin D from sunlight can only be synthesized in the skin during the spring, summer and fall months, around midday, from 10 a.m. – 2 p.m., when the UV index is above three and your shadow is shorter than your height.

Statistics Canada reports that 12 million Canadians, or 35% of the population, have insufficient vitamin D levels, including 10% who are severely deficient, which sets them up for higher disease risk.

Dr. Vieth University Of TorontoAccording to Dr. Reinhold Vieth, Scientific Advisor for the Canadian Vitamin D Consensus and professor at the University of Toronto in the Department of Laboratory Medicine and Pathobiology, “If organizations warn people to stay out of the sun, then they should also let people know that they will not be producing vitamin D. Both the risks and benefits of UV exposure need to be addressed in the best interest of health. Unfortunately, the message Canadians keep hearing lately is that there is no benefit to being in the sun. The paper by Baggerly et al presents a clear case that good overall health does correlate with spending time in the sun.”

VitaminD and MS

A group comprised of the Multiple Sclerosis Society of Canada, Vitamin D Society and Pure North S’Energy Foundation, have endorsed a draft Canadian Vitamin D Consensus which recommends that Canadians enjoying the sun safely, while taking care not to burn, can acquire the benefits of vitamin D without unduly raising the risk of skin cancer.

Vitamin D deficiency is an indication of sunlight deficiency.

“People today work less outdoors and spend less time outdoors than at any previous time in history, which is why vitamin D deficiency is rising globally. In addition, when people are outside, many use sunscreens, which can significantly prevent the production of vitamin D in the skin,” said Dr. Vieth. “With increasing amounts of evidence suggesting that vitamin D may protect against cancer, heart disease, diabetes, multiple sclerosis and other chronic diseases, it’s more important than ever to examine this issue more closely.”

Learn more at sciencedaily.com

“We urge public health entities to re-evaluate their current sun exposure policies and recommend UV exposure levels that promote a balanced, moderate approach that are both beneficial and safe,” said Baggerly.

About the Vitamin D Society:

The Vitamin D Society is a Canadian non-profit group organized to increase awareness of the many health conditions strongly linked to vitamin D deficiency; encourage people to be proactive in protecting their health and have their vitamin D levels tested annually; and help fund valuable vitamin D research. The Vitamin D Society recommends people achieve and maintain optimal 25(OH)D blood levels between 100 – 150 nmol/L (Can) or 40-60 ng/ml (USA).

Nine Percent Of Canada High Incomers Considering Using Foodbanks

Few Canadians are immune to the rising cost of living, according to a new report from Statistics Canada, with 9 percent of those in the highest income quintile considering using a food bank.

Data from spring 2024 shows that while 42 percent of Canadians are concerned over rising food prices, about 9 percent of those in the highest income bracket report they may have to turn to a food bank or similar community organization for help. That number rises to 14 percent for those in the second-highest income bracket, StatCan said.

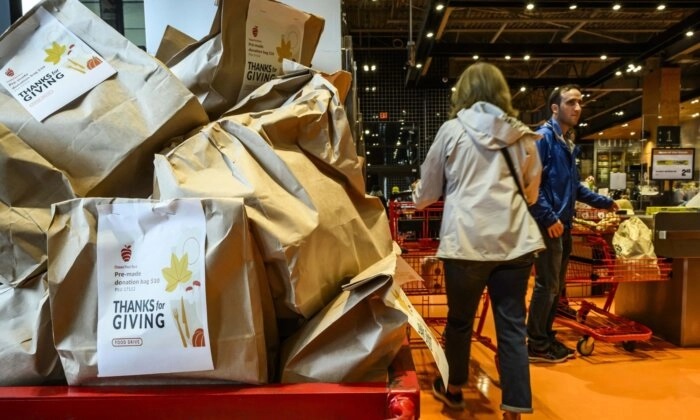
A cart is filled with bags of food during a Thanksgiving food drive for the Ottawa Food Bank, at a grocery store in Ottawa on Oct. 7, 2023. The Canadian Press/Justin Tang

Nearly half of Canadians report struggling to meet day-to-day expenses, up 12 percentage points from 2022 to 45 percent.

The survey found that the number of Canadians who feel “quite a bit” or “extremely” stressed over financial issues increased slightly since 2022, from 33 percent to 35 percent this year.

Families with children and those living with a disability are struggling the most, StatCan said.

Fifty-five percent of families with children say rising costs have impacted their ability to cover daily expenses, compared to 42 percent of households without children and 37 percent of single Canadians.

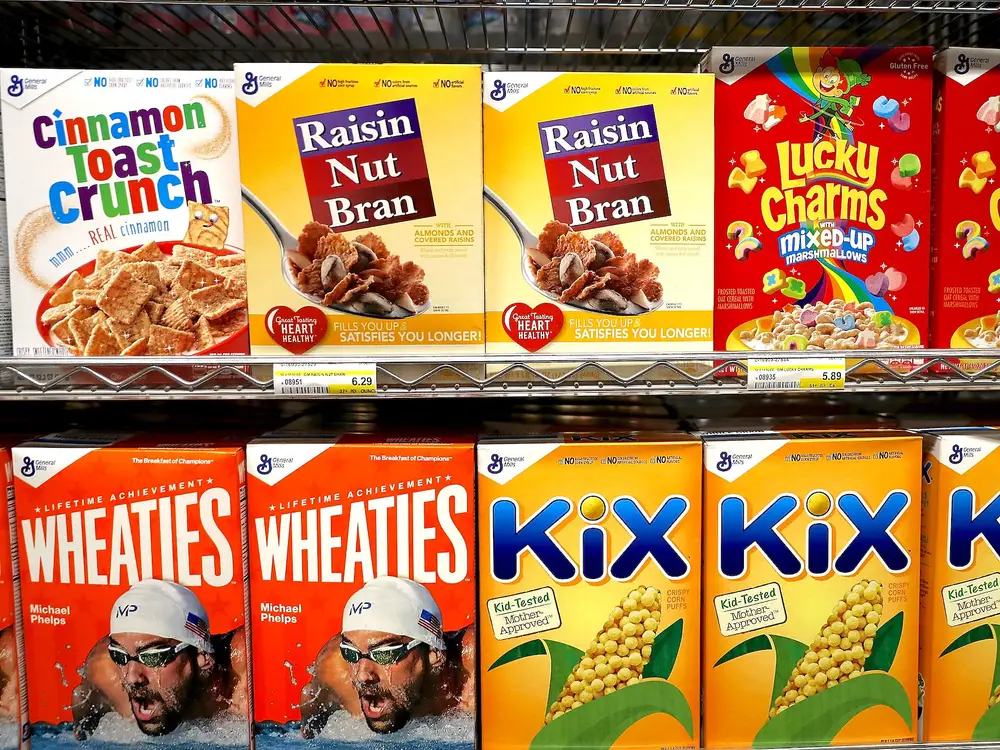
Shrinkflation– a sneaky way of charging more by giving less. General Mills shrunk its “family size” boxes from 19.3 ounces to 18.1 ounces. Justin Sullivan/Getty Images

Those with disabilities are also more likely to be facing financial difficulties, with 57 percent saying they are struggling to meet daily costs, compared with 43 percent of those without a disability.

Housing is one of the biggest concerns Canadians cite, with nearly four in 10 saying they are concerned about their ability to afford a home because of rising prices. The number has risen from 30 percent in 2022 to 38 percent this year.

StatCan found that renters are more uneasy about increasing prices than homeowners, with nearly two-thirds of renters “very” concerned over housing affordability compared with about one-third of homeowners.

Food prices are another top concern for those surveyed, with more than one in five Canadians saying they may not be able to afford groceries. The number has risen to 23 percent, up from 20 percent two years ago.

Of those worried about food prices, 8 percent say they are very likely to need help from an organization such as a food bank. Another 15 percent say they are somewhat likely to need community help.

More than one in four families with children say they expect to turn to food banks and similar organizations, compared to one in five for other household types, StatCan said.

About one-third of Canadians with a disability say they expect to get food from a community organization in the next six months, compared to one in five of those without a disability, the agency said. For the Silo, Chandra Philip / The Epoch Times. The data was collected between April 19 and June 3.

Related Stories

Rent Prices Hit Record High Across Canada, New Report Finds

Rent Prices Hit Record High Across Canada, New Report Finds

Grocery ‘Shrinkflation’: Some Products Reduced Over 20 Percent in Size, Study Finds

Grocery ‘Shrinkflation’: Some Products Reduced Over 20 Percent in Size, Study Finds

Traditional Family Fades In Canada As Some Women Advocate For Revival

On her fridge door, along with numerous family pictures, Danielle Brandt has a handwritten quote by Dr. John Trainer: “Children are not a distraction from more important work. They are the most important work.”

A proud Calgary mother of three boys (Aiden, 10, Theodore, 4, and Silas, 2), Mrs. Brandt is a homemaker. Her husband, Adam Brandt, is the breadwinner. At the core of their parenting philosophy is the belief that strong families make strong societies, Mrs. Brandt says.

She was a music teacher before becoming a stay-at-home mom, but when she returned to work shortly after giving birth to her first child, she says she realized she wanted to be fully involved in raising her children.

“The idea that your identity is found at home with your family and not out in the world with your peers, and that your parents and your family are what matters first … that’s the reason I wanted to be home with my children.”

While Mrs. Brandt persists in adhering to her traditional role in the family, there is declining interest among young Canadian women to pursue the same path.

Canadians are “increasingly less likely” to form families, and if they do, they are choosing to have fewer children, if any at all, according to a May 2024 report jointly published by the Macdonald-Laurier Institute (MLI) and the Centre for the Study of Living Standards.

ANALYSIS: To Reverse Canada’s Declining Birth Rate, Cultural Changes May Be More Important Than Economic Ones

How Marxism Broke Down the Nuclear Family

How Marxism Broke Down the Nuclear Family

The same report, based on evidence from existing data and literature, found that traditional families enjoy more prosperity and better health.

Adults who are in a couple tend to earn more money per person than singles of the same age and, if married, they tend to live longer, have healthier lifestyles, and are less stressed. Similarly, children benefit from being raised by their two biological parents in a stable marriage, appearing to have a higher standard of living and educational attainment, and being less likely to engage in risky behaviour, the report found.

But a significant fraction of Canadian children will see their families break up by the time they are 14, and more than a quarter live in one-parent families, the report said. The author, Tim Sargent, deputy executive director of the Centre for the Study of Living Standards, concluded that the rates of family dissolution in Canada are higher than those in the United States and the UK, culturally comparable countries.

Janice Fiamengo, a retired University of Ottawa English professor who now gives talks on the role of women in society, says the downward trends in family formation are largely due to how women’s priorities are being redefined in Canada.

“Their primary goal in life is to be independent, to have a career, and to regard marriage and childbearing as secondary, if not undesirable in general,” Ms. Fiamengo told The Epoch Times, describing the trends and messages aimed at young women today.

Trends Among Canadian Women

Women are now taking longer to complete their higher education. From 2000–2022, the participation in education of women aged 20 to 24 rose by 12 percent (to 51 percent), according to Statistics Canada.

Only 37 percent of men in the same age range participated in education in 2022, and that rate grew by just four percentage points since 2000. Similar trends are seen among men and women aged 25 to 29.

Source: Statistics Canada 2023h, Table 37-10-0196-01. (Chart: Carolina Avendano/The Epoch Times)
Women’s participation in the labour market has also increased dramatically in recent decades, with fewer and fewer women choosing to be stay-at-home moms.

Employment among women aged 25 to 54 has almost doubled from 40 percent in 1976 to about 80 percent as of May 2024, according to Statistics Canada. Employment rates for women in general remain higher than they were prior to the pandemic in 2017 and 2019.

In addition, more women aged 25 to 34 now delay living with their partner. The proportion of those who live with their parents increased by 3.3 percentage points, from 12.8 percent in 2011 to 16.1 percent in 2021.

Marriage rates are on the decline while divorce rates are increasing, and women are waiting until later to have children.

At the same time, Canada’s fertility rate has been declining persistently for the past 15 years, with the national rate hitting an all-time low in 2022 at 1.3 children per woman.

A study by the think tank Cardus found that the top factors that diminish a woman’s desire to be a mother are wanting to grow as a person, wanting to save money, focusing on a career, and believing that kids require intense care.

“Any woman who decides that what she primarily wants to do is to marry and to have children, that woman is seen as having failed, having let down other women, and having failed herself,” says Ms. Fiamengo.

She says the prevalence of feminism in Canada has played a role in shaping these views.

Changing Views on Traditional Family Roles

It wasn’t until the second-wave feminism of the 1980s that an idea with communist roots took hold—the dissolution of the traditional family structure, Ms. Fiamengo says.

Feminism takes many forms and contains different ideas—in the 19th century, it was about women’s suffrage. The idea that the traditional family is at odds with gender equality and women’s fulfilment has its origins in communist ideology.

In his 1884 book titled “The Origin of the Family, Private Property and the State,” Friedrich Engels, based on notes by Karl Marx, made the first allusion to the monogamous family as “the world historical defeat of the female sex,” in which the woman was reduced to servitude and turned into an instrument for the production of children.

He thus advocated for the liberation of the wife, the abolishment of the family, and for the care and education of the children to become a public affair.

“[Engels] explicitly makes that connection, that the man—the patriarch—is the capitalist oppressor. The woman is in the situation of being the oppressed worker or the sex slave in the family,” says Ms. Fiamengo.

“He saw no distinction between prostitution, in which a woman is bought by a man to have her body used for the man’s pleasure, and the situation of a woman in a marriage.”

Betty Friedan’s 1963 book “The Feminine Mystique,” a precursor of feminism as a struggle between genders, urged women to break free from the domestic sphere and find their own identity outside the home. Friedan promulgated that fulfillment could not be found through marriage and motherhood alone.

Ms. Fiamengo says feminism’s lack of encouragement for women to start a family makes them miss out on what she thinks is one of the greatest joys of human life—childbearing.

“The fact that our government doesn’t encourage marriage … or encourage couples to stay together for the good of their children, is doing a terrible disservice to the future generations,” she says.

Peter Jon Mitchell, program director for Cardus Family, says the prevalent view of marriage in Canada is that “it’s nice, but unnecessary.”

“We don’t really talk a lot about marriage and the benefits of marriage in our culture.” Mr. Mitchell also that, compared to the United States, where the two-parent privilege—the fact that children fare better in two-parent rather than single-parent households—and the benefits of marriage are part of the public discourse, Canada lags behind.

The May MLI report cites some studies showing that children in two-parent households fare better. One published by the National Library of Medicine in 2014 found such children do better physically, emotionally, and academically.

Likewise, in a 2015 research paper, David Ribar, honorary professor at the University of Melbourne, found that children who grow up with married parents enjoy more economic and family stability. Mr. Ribar argues that the benefits of marriage for children’s wellbeing are hard to replicate through policy interventions other than those that support marriage itself.

Consequences of Putting Family Role Second

Sociologist Brigitte Berger noted in her book “The Emerging Role of Women” that work is important for both sexes. Yet liberation through work means different things to different people.

To the working-class women and the poor, for whom work is a necessity, liberation means freedom from financial burden and the freedom to devote time to things that matter outside of work, such as family, community, and hobbies. Among women for whom work is not a necessity, modern thinking has led them to find identity and liberation through paid labour.

According to a 2021 survey by the Canadian Women’s Foundation, 28 percent of mothers reported difficulty keeping up with work demands, and half of mothers felt exhausted trying to balance work and childcare responsibilities.

“I think most mothers would prefer to be part-time,” says Mrs. Brandt. “They don’t actually want to leave their kids 100 percent of the time with someone else.”

She says the widespread notion that women can do it all is not realistic and can lead many to burnout. “I can’t fully parent my children well and fully do another job [outside the home], at least not the way I want to,” she says. “Something has to give; there’s not enough of me.”

Mrs. Brandt says she is not worried about her chances of returning to work at some stage.

“We live a long time nowadays. You can’t always have kids, you can’t always be with your kids when they’re young or get that time back when they’re young,” she adds. “But you could do a career later, and that’s the amazing thing about our culture, too.”

Last year, a study by the think tank Cardus found that half of Canadian women are not having as many children as they would like, and that this group reported lower life satisfaction than women who achieved their fertility goals.

Cardus senior fellow Lyman Stone noted low fertility rates are not because women want few kids, but the timeline most of them follow for school, work, self-development, and marriage leaves too few economically stable years to achieve the families they want.

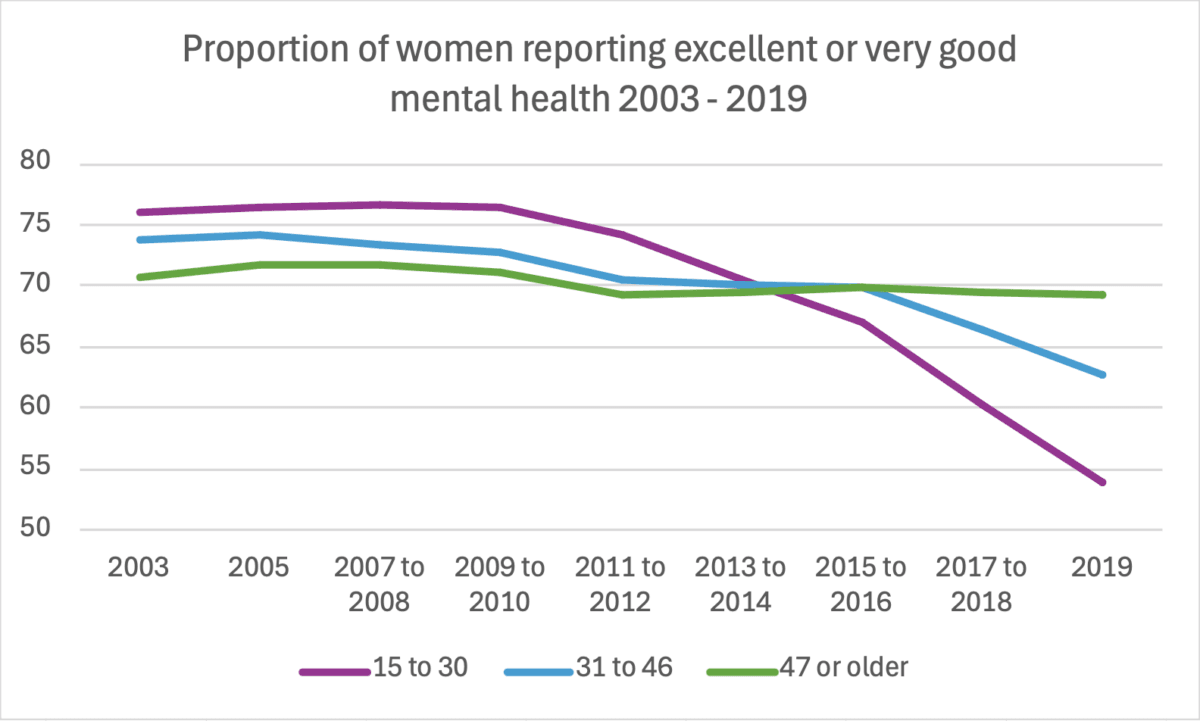
One of the most striking findings of the May MLI report is that Canada has seen a marked deterioration in the mental health of young women over the last decade.

More than three-quarters of women aged 15 to 30 reported excellent or very good mental health between 2009 and 2010. Throughout the following nine years, that figure dropped 22.5 percentage points, to 54 percent. For women aged 31 to 46, mental well-being also declined, but only by 10.1 percentage points.

Source: Canadian Community Health Survey, 2003 to 2019. (Chart: Carolina Avendano/The Epoch Times)

Motherhood and Women’s Happiness

A Cardus 2023 study concluded that women’s happiness and fertility are linked. The think tank surveyed 2,700 women aged 18 to 44 about family and fertility, and found that mothers are happier than non-mothers everywhere (except when they are under 25 or living in poverty).

“The role of the mother really is to nurture and to develop children,” says Mrs. Brandt. “My husband is a wonderful nurturer, he’s fantastic at it, but my boys, even the ones that have the closest relationship with him, they still need mom … I’m still the safe place.

“I am not saying that men can’t do it, but sometimes women are built for it, and there’s nothing wrong with that.”

Danielle Brandt with her youngest son, Silas, at her Calgary home on June 1, 2024. Mrs. Brandt homeschools her oldest son, Aiden, because she saw he was falling behind in class. Seeing the positive response, she now plans to also homeschool her other two children. (Carolina Avendano/The Epoch Times)

She draws inspiration from her mother, who was also a teacher turned homemaker. Mrs. Brandt says her mother was always available for her and her three siblings, and would show up at their most important moments, including sporting events, school functions or field trips. “We felt like we were the priority because we were,” she says.

But being a stay-at-home mom is also demanding, Mrs. Brandt adds. Although it’s rewarding, she says the challenge is that there is no time off. “But at the end of the day, when I look at my children and see them peacefully sleeping, [I think to myself] ‘That’s it, that’s what this is about,’” she says. “They are the future generation. I want to pour into that, and there is no more valuable work than that.” For the Silo, Carolina Avendano.

Featured image- Danielle and Adam Brandt with their sons Silas (L), Aiden (C), and Theodore at their home in Calgary on June 1, 2024. (Carolina Avendano/The Epoch Times)

Making Sense Of Canada Doctor Shortage Paradox

Canadians are in a primary-care paradox.

About 14 percent of Canadians aged 12 and older – approximately 4.6 million people – did not have a regular health-care provider in 2022, according to Statistics Canada. Even more alarming, about 6.6 million Canadians rely on family doctors aged 65 and over, meaning that even more people could soon find themselves adrift as their physician retires.

Canada has the highest number of general practitioners per capita among comparator countries, yet ranks worst in terms of having a doctor or a regular place for medical care (only 86.2 percent of surveyed Canadians had one in 2023).

What is happening?

Several factors are at play.

First, it’s no secret that the physician workforce, much like the rest of our population, is aging. There aren’t enough new graduates to replace retiring physicians and meet the needs of a growing population. [Canada currently has one of the highest Immigration rates in the world with rates growing steadily and currently sit at around 1.2% population increase each year. CP]

Moreover, physicians have been spending fewer hours on direct patient care. Administrative tasks, such as paperwork for insurance claims, sick notes, and duplicate form requests from different organizations, consume approximately 18.5 million hours of physician time annually in Canada, equivalent to 55.6 million patient visits. Economic and cultural factors are also steering medical trainees towards specialties rather than general family practice. Without changes, the gap between the supply and demand for family physicians will only widen.

My recent C.D. Howe Institute analysis shows that under a normal retirement scenario – where 57 percent of family physicians aged 75 and over retire – the projected supply of family physicians in 2032 will meet 90 percent of the demand. If all family physicians aged 75 and over were to retire, only 78 percent of projected demand would be met, leaving us 13,845 family physicians short.

This means that about 9.6 million Canadians could be without a family physician in the next decade. The consequences of this shortage could be dire, leading to delayed or inadequate care, increased costs, and a strain on other parts of the healthcare system.

With only about 1,550 family physicians completing residency in 2022, the current pipeline of graduates is insufficient. What needs to be done?

Increasing numbers is essential, but will not suffice to meet the demands of a growing and aging population. We need a comprehensive strategy, and five well-established strategies can help.

First, we need to increase the number of training positions for prospective family doctors and accelerate pathways for international medical graduates to enter family medicine, whether direct-to-practice or through residency positions.

Second, administrative processes need to be streamlined to reduce family physicians’ unnecessary workload, freeing more time for direct patient care.

Another strategy is to introduce payment models such as capitation or bundled payments that better support family physicians, making family practice more attractive and encouraging more patient enrolment and after-hours care.

As well, allowing other primary-care providers, such as nurse practitioners and pharmacists, to take on a broader range of responsibilities could assist with sharing the workload and improving patient access.

Finally, developing and expanding team-based models of care that bring together health-care professionals to provide comprehensive and continuous patient care could also benefit Canadians.

The good news is that some of these steps are starting in some provinces.

Nova Scotia is advancing on all fronts; creating a new designated pathway to residency for international medical graduates; committed to reducing physician red tape by 80 percent  by 2024; is a leader in paying family physicians with alternate payment; introduced pharmacist-delivered primary care for 31 minor ailments; and expanded team-based care at new and existing locations. Similarly, British Columbia and Ontario have made notable advancements in several of the five strategies.

Improving primary-care access is a nationwide challenge that requires concerted efforts and innovative solutions. By learning from the policies and experiences of different provinces, Canada can develop and implement effective strategies to ensure every Canadian has access to a family physician and the primary care they need. Canada’s health-care system – and the health of its people – depends on it.

For the Silo, Tingting Zhang -Junior Policy Analyst at the C.D. Howe Institute.

Supplemental- Canada’s Lack Of Residencies For Foreign-Trained Doctors Fuelling Healthcare Labour Shortage

Why Are More Canadians Moving Abroad?

An increasing number of Canadians can’t afford a house or find a decent-paying job. Some can’t find a date or are fed up with the bitter politics, while others are in search of adventure, are sick of the cold winters, or simply miss the feeling of ‘being home’.

The solution they seek? Leave Canada.

The rising cost of living, record-high immigration, a stagnating economy, and political tensions are prompting rising numbers of Canadians—both native and naturalized—to leave the country.

Canada is increasingly becoming a country of emigrants, as well as a country of immigrants, experts say.

“We’re definitely seeing a lot more interest from people wanting to leave Canada,” Michael Rosmer, founder of Offshore Citizen, a Dubai-based company that offers relocation services to people around the globe. “This is disproportionate to their numbers overall.”

He said many of his clients are motivated by the increasing ability to work from anywhere, plus political tensions within Canada accompanied by a feeling of lost freedoms. Also a factor is the rising standard of living of many countries that were once far below Canada in terms of health care, education, and other services.

While Canada was once considered among the best places in the world to live, “it’s like the world has flipped,” Mr. Rosmer said. “The alternatives have gotten meaningfully better. Today if you go to Kuala Lumpur you’re going to find that it is arguably better than any Canadian city.”

Canada’s Immigration Conundrum: Economic Boon or Bust?

Immigration Minister Tells US Public Broadcaster Canada an ‘Open Country’

Some 94,576 people emigrated from Canada from mid-2022 to mid-2023, an increase of 1.8 percent from 92,876 in the year-earlier period, and up sharply from 66,627 in the period from mid-2020 to mid-2021, which fell during the pandemic lockdowns, according to data from Statistics Canada.

A study released last year by the immigration advocacy group Institute for Canadian Citizenship (ICC) showed  immigrants are also increasingly reluctant to stay, with the proportion who stick around to obtain full citizenship within 10 years of receiving permanent resident status plunging to 45.7 percent in 2021 from 60 percent in 2016 and 75.1 percent in 2001.

Cameron MacDonald, a 29-year-old from the Niagara Falls region of Ontario who left Canada in March for Japan, cited the high cost of living as the main reason for his move, which uprooted him from friends, family, and a job as an anti-fraud analyst with a major Canadian bank. He is now studying Japanese and looking for a job with a foreign firm, while living in Tokyo, which has a population density of 6,363 people per square kilometre compared to Toronto’s 4,427.8 per square kilometre.

“Here in Tokyo, the world’s biggest city, I pay $650 a month for a room that I would have had to pay $2,000 for in Toronto.” I had a routine and a cushy bank job and I was even living with my dad after a while but I still couldn’t get ahead financially.”

He said the high cost of housing in Toronto means that all of his friends of a similar age in Canada are still living with their parents and, as many of them consider starting families, they are watching his move with the thought of moving abroad themselves.

“My five-year goal includes a wife, a house, and kids and there’s no way I could afford that in Canada,” Mr. MacDonald said. “You can’t really date and find a wife when you’re living with your dad.”

“In Japan, I wake up with a smile on my face every day,” he said. “It’s like I have found a new passion—I can start a family here.

High Immigration

Like many people, Mr. MacDonald blames Canada’s rapid pace of immigration for driving up the cost of living and forcing him to move abroad.

As of Oct. 1, 2023, Canada’s population was estimated at 40,528,396, a record increase of 430,635 people in the previous three months alone, according to Statistics Canada. That growth rate, at 1.1 percent in a quarter, was the highest since 1957, amid Canada’s baby boom plus an immigration surge fueled by a refugee crisis in Hungary at the time.

In just the first nine months of last year, Canada’s population grew by 1,030,378 people, more than any other year dating back to confederation in 1867, the statistics show. And 96 percent of that growth came from immigration. Overall, the population grew 30 percent since it reached the 30 million figure in 1997.

Canada’s Plan to Welcome 500000 Immigrants by 2025. ascenda.com

Indeed, rapid population growth has outstripped economic growth in recent years, lowering the standard of living in Canada as more people compete for less housing space and place greater strains on health care, education, and other services, according to a study published in May by the Fraser Institute. The study shows Canada’s real gross domestic product per person dropped 3 percent between April 2019 and the end of last year, from $59,905 to $58,111. The only steeper drops in the 40 years covered by the study were from 1989 to 1994, with a decline of 5.3 percent, and the financial crisis of 2008 to 2009, when it dropped 5.2 percent.

Another factor propelling emigration may be the aging of the baby boomer generation. As more Canadians reach retirement age, emigration to the United States, particularly to sunny states such as Florida, is accelerating.

A study by Statistics Canada also shows that high immigration tends to push up emigration because some immigrants move back to their home country. The study showed that 15 percent of the people who immigrated to Canada between 1982 and 2017 returned within 20 years of admission.

Whatever the root cause, the interest in leaving Canada has caught the attention of the global industry of specialists offering services to wealthier emigrants around the world.

Videos created by people seeking to offer second-passport services and other relocation help are growing in popularity. “Nine Steps to Escape Canada,” a YouTube video watched 362,000 times, “5 Reasons to Leave Canada in 2024,“ watched by 261,000 and ”Canada is Dying!,” with 531,000 viewers are some of the most popular.

Jay Suresh, the founder of Goodlife Investor, which offers emigration services to people around the world looking to obtain second passports, foreign tax advantages, and other benefits, says the number of Canadians looking for dual citizenship jumped after the Canadian government banned unvaccinated people from flying or travelling by train in late 2021 until the summer of 2022.

“This was an eye-opener for a lot of people. They got frustrated with just that one citizenship and they wanted multiple citizenships,” he said in a video promoting his company. Now, he says, Canadians are nearly tied with U.S. citizens in searches for second passports, even though the United States has 10 times Canada’s population. For the Silo, Adam Brown.

Featured image: People line up to go through security screening at Pearson International Airport in Toronto on Aug. 5, 2022. (The Canadian Press/Nathan Denette)

Demand For Canada Seniors Care Is Critical

As Canada’s aging population continues to grow, there are concerns about the financial and physical capacity to meet its growing care needs.

Seniors’ need for housing and care is a complex issue involving many government policies and, therefore, government has many avenues for the exertion of control and adjustment over the issue. Much room for improvement is evident in the quality of, capacity for, and financial support for meeting these needs. This analysis provides a summary of the challenges and gaps in the current state of senior support policies and provides insights to inform future policy.

This Commentary examines the household spending patterns of seniors, the availability of different housing and care options, the costs of providing care in different settings, and government policies that subsidize support services in homes, retirement communities, and long-term care. The results show that the availability and costs of different services and types of care vary significantly across the country. In particular, seniors with below-median incomes face affordability challenges related to shelter costs, with these costs becoming a potential barrier to access to retirement homes and other support services if not publicly available. Further, there is unmet need for home care across Canada, which invests less in home and community care than other OECD countries.

To ensure there is adequate capacity to provide care for high-needs seniors, provinces should invest in expanding home and community care and prevention.

Previous research has shown that about 30 percent of entries to long-term care homes (LTC) could be delayed or prevented (CIHI 2017). Investing in expanded home and community support services and providing financial supports for low-income seniors to access the care they need where it is most appropriate, can reduce the demand for more intensive (and expensive) LTC or hospital care. There are waitlists for LTC, and “alternate level care” seniors occupying hospital beds, which contributes to higher costs, lower hospital capacity for other treatment, and lower quality of life and declining health for the affected seniors. In addition, a significant proportion of below-median-income seniors face housing affordability challenges. Ensuring housing needs are appropriately met can improve the quality of life of seniors and prevent premature entry into higher levels of care. Differences in the availability of services and how they are funded across the country can inform strategies to improve accessibility and capacity. Notably, Quebec has more seniors’ care spaces, lower vacancy rates and lower rent charges than other provinces, while providing comparatively more support to senior households through tax credits.

Overall, limited fiscal capacity, growing demand due to demographic aging, and the growing costs and complexity of care needs for aging seniors all present a significant conundrum for policymakers. There is a daunting challenge in determining the appropriate level of support, ensuring it is well targeted, and allowing for seniors to choose what is best for them. Government policies should encourage seniors to remain independent as long as possible, but also ensure they have adequate financial resources and access to support services if they are required.

Levels of Care Needs

There are multiple options for housing accommodations as seniors age, and the choice will depend on their preferences, families, level of need, and the affordability and accessibility of the various options. This section discusses the different care needs that seniors might have as they age. It also illustrates the continuum of care: seniors choosing assisted/supportive living accommodations or receiving home care will have a range of needs, and care must be flexible enough to suit an individual’s needs.

Activities of Daily Living (ADLs) are a set of essential everyday tasks and activities that individuals typically need to perform to live independently and maintain their overall well-being. These activities are often used in healthcare and long-term care settings to assess an individual’s functional abilities and to determine their level of independence. When someone experiences limitations in one or more of these areas, they may require varying degrees of assistance or care, ranging from minimal support to full-time care. Health professionals use ADL assessments to develop care plans and tailor assistance to meet an individual’s specific needs and promote their overall quality of life. The specific ADLs may vary slightly in different contexts, but the core activities are as follows.

  • Personal hygiene and grooming: including bathing/showering, caring for teeth, medication management, etc.
  • Dressing: choosing appropriate clothing and putting it on independently.
  • Eating: feeding oneself and preparing simple meals.
  • Mobility and transferring: being able to walk, get in and out of bed, or independent transferring from one surface to another (such as from a bed to a wheelchair).
  • Toileting and continence: The ability to get on and off the toilet, maintain personal hygiene, and manage incontinence, if necessary.
  • Medication management: the ability to follow medical care plans without the need for assistance or reminders to take necessary medications.
  • Instrumental Activities of Daily Living: activities that are not essential to basic self-care, but are crucial to independent living in a community such as managing finances, planning and preparing meals, doing laundry, going shopping for essential items, etc.

Notably, most of the ADLs have little to do with direct healthcare needs. Instead, they are a set of daily activities that could be provided by different types of support services including meal delivery, housekeeping, laundry services, and social activities. Seniors requiring support with some ADLs could benefit from one or more support services, even if they do not have advanced healthcare needs. Healthcare is an important component of supporting seniors to remain independent, however, many of the activities that are required for independence fall outside the traditional scope of healthcare.

The options for support available to seniors are directly related to their care needs. Those who are able to live independently can choose their accommodations based on lifestyle and preferences. Those requiring occasional or minimal assistance can remain in their homes and receive help from family, other informal caregivers, and possibly publicly funded home and personal care services, or they could choose to privately pay for some services such as regular housekeeping or food delivery services. They might also choose to move to a retirement home or community where meals and other services are provided, as well as ongoing opportunities for socialization. As care needs become more intensive, seniors may require ongoing or live-in support from a combination of public or private home and nursing care services, family, or an informal caregiver at home. In the retirement home setting, there are many options to address increasing care needs. However, as care needs become greater, affordability plays a factor in how long a senior might stay in a retirement home before moving to LTC where care needs are generally fully subsidized by government, and room and board charges are limited by regulations.1

At home, those requiring hands-on or total assistance require significant and ongoing care. At this stage, a caregiver must be available at all hours to assist with many basic ADLs, and the options for care become more limited. Those without an available caregiver in the home will likely be best served by residing in long-term care homes that have health providers on site at all times of day. Depending on their health conditions, hospice and palliative care might also be appropriate for end-of-life care. Increasing numbers of retirement homes are offering heavy care and dementia care services, and publicly funded home care can be accessed to supplement some of the costs. This still, however, presents a significant financial burden to seniors. Often, even though a retirement home can safely and appropriately meet the care needs of a senior, LTC becomes the preferred option. Most often, this is because of the cost differential between what the government will subsidize in a LTC setting versus the limited home-care services available to offset privately paid retirement home care costs.2

Availability and Options for Care Based on Needs

The options for care and assistance with ADLs reflect progressive levels of need. As care needs become more intense, the options become more limited (and/or costly). Those requiring ongoing care can choose to live in a long-term care home, or might be able to remain in a residential setting – home, retirement home, assisted living facility – if they and their families have the resources to supplement publicly provided services, and if the appropriate services are available privately. Of course, those that are independent have a full range of choices for where they might want to live, except those places reserved for people with higher care needs. More than three-quarters (78 percent to 91 percent) of Canadians would prefer to receive care while continuing to live in their homes as they age, but only one-quarter (26 percent) expect that they will be able to do so (Sinha 2020, March of Dimes 2021). The different types of seniors’ accommodations and short-term respite care programs are described in Box 1. It is important to note that there is overlap between many care options and levels of need – two seniors with similar care needs might use different combinations of services. This is particularly the case for people with minimal to moderate needs for support. Similarly, the options will vary in terms of availability and costs depending on the location, the ownership and operation models of the different residences, and the level of public coverage and involvement in different levels of care. The next section provides a summary of the availability and costs of various seniors’ living arrangements across the country, focusing on provinces with larger populations (BC, Alberta, Ontario and Quebec).

Long-term Care

There are 2,076 long-term care homes in Canada. At first glance, LTC in Canada appears to have a comparable amount of beds and financial resources in comparison to international peer countries. Canada has close to the average number of LTC beds relative to the size of the senior population, but still fewer than countries such as New Zealand, Finland, Germany, and Switzerland. It also has a comparable proportion of the senior population receiving LTC care and homecare, relative to international peers (Wyonch 2021). It spends more per capita than the OECD average on funding LTC but spends less than other OECD countries as a proportion of GDP. The GDP proportion of health spending for inpatient LTC is above average (Wyonch 2021).

Despite higher-than-average spending, there are long waitlists for LTC in many Canadian provinces. In Ontario, there were, as of Oct. 2022, almost 40,000 seniors waiting for LTC, and 76,000 receiving care; this means the waitlist currently exceeds 50 percent of care capacity (OLTCA).3

The median wait time was 130 days in 2021/22 (213 days for entrants from the community, and 80 days for hospital entrants) (HQO). In Quebec, the waitlist is much smaller (4,235 as of June 2023). However, seniors might still wait up to two years for a placement (Bonjour Résidences).

The cost of long-term care varies across provinces, but charges payable by the resident to cover room and board are generally standardized by regulation within each province. For example, in Ontario the maximum monthly co-payment for LTC is $1,986.82 – $2,838.49 depending on whether the room is shared or private. In Quebec, room and board charges for public and contracted private long-term care homes (CHSLD or centre d’hébergement et de soins de longue durée) are $1,294.50 – $2,079.90, depending on the type of room. Quebec also has unsubsidized (uncontracted) private CHSLD, where the average monthly costs are between $5,000 and $8,000, depending on resident’s needs (Bonjour Résidences).4More than half of LTC homes (54.4 percent) and the majority of retirement homes are privately owned and operated. There is no consistent ownership pattern across the country: in five provinces, the majority of LTC homes are privately owned and operated, with the other provinces having majority public ownership. All LTC homes in the Territories are publicly owned. Both publicly and privately owned LTC homes provide ongoing care for some of the most vulnerable members of society. At both public and private LTC homes, healthcare is publicly funded and most support services will be included in room and board rents. Seniors must require significant care to qualify for LTC.5

Individuals requiring support who don’t have a caregiver in the home are much more likely to be admitted prematurely to LTC homes. Indeed, about one in nine new entrants could potentially have been cared for at home or in a retirement home setting. These new residents are more likely to have previously lived alone or in a rural area where formal and informal supports are less likely to be available (CIHI 2020b).

Retirement Homes

Retirement homes offer a wide variety of services and programs targeted at different client types. These include those who are fully independent and wish to live in a congregate setting for the lifestyle and social benefits, those with mild to moderate care needs, those with heavier care needs, and those who require specific dementia care programs and supports. In Ontario, for example,15 percent of homes provide dementia care, 34 percent provide assistance with feeding, and the majority provide services to assist with other ADLs (Roblin et al. 2019). Prices of retirement home care vary significantly by location, as well as by amenities and services offered as they are market driven (and are not generally directly government subsidized). Various provinces have senior rental accommodations that provide care needs: in Quebec the services are called “seniors’ residences”; in BC “assisted living”; in Ontario “retirement homes”; and in Alberta, “supportive living.”

Many retirement homes offer more extensive health and personal care services. These additional services increase costs for seniors since they are either charged as additional services or will be incorporated into higher room and board costs. In Ontario, if these additional services are provided by the retirement home, the additional services are not directly publicly subsidized. In some cases, residents in retirement homes might also receive home care or assisted living support that is provided by a separate agency, either publicly or privately. Most retirement homes are privately owned and operated. Their activities and levels of care provision are regulated by provinces, but prices will be determined by market factors and the amenities and services offered in each location.

In Ontario, retirement communities are regulated by the Retirement Homes Act, 2010 (RHA), and are licensed and inspected by the Retirement Homes Regulatory Authority (RHRA).6Each retirement community can offer up to 13 care designated services, for example, assistance with dressing and personal hygiene, medication management, and providing meals. Services might also be publicly provided through home care. About half of seniors currently living in retirement homes have care needs that would qualify them for publicly provided home and community care. Home care services supplement the care services in the retirement home at no cost to the resident and assist with affordability of the retirement living option for seniors with care needs.

In Quebec, private seniors’ residences are rental facilities that are mainly occupied by people over 65, and offer various services such as nursing care, meal services, housekeeping, and recreation. Private seniors’ residences must hold a certificate of compliance from the Government of Quebec ensuring they comply with health and safety rules. Similarly, in Alberta, the provincial government sets accommodation standards for supportive living facilities. Supportive living operators require a licence if they provide accommodation and support services to more than three people, provide meals or housekeeping services, and arrange for safety and security services. Alberta also has Designated Supportive Living where access is determined by an assessment by a health professional, room and board charges are determined by the Alberta government, and accommodations provide 24-hour publicly funded health and personal care services on site.

In British Columbia, retirement homes are divided into categories: independent living, and assisted living.7Assisted living is divided into three classes: i) seniors and persons with disabilities who have chronic or progressive conditions, ii) mental health care, and iii) substance use care. Assisted living residences provide housing, hospitality services and support services, and they may be privately paid, publicly subsidized, or a combination of both. Independent living seniors’ residences are essentially retirement homes targeted to seniors who need minimal assistance and are not generally publicly subsidized. For seniors requiring assistance, assisted living spaces are publicly subsidized based on income: a maximum of 70 percent of after-tax income goes to housing and support services in assisted living. However, there is a minimum fee of $1,093.50 per individual ($1,665.60 per couple) and maximum monthly rate for publicly subsidized assisted living is based on market rates for rent and hospitality services in the same geographic area.

Though individual retirement homes and assisted living facilities might have waitlists, there are fewer concerns about overall capacity. Across provinces, both standard and heavy care spaces are at least 10 percent vacant (Figure 1). 

Alberta has the highest vacancy rate for standard care spaces (26.8 percent) and the lowest vacancy rate (10 percent) for heavy care spaces, suggesting a need to transition some standard spaces to heavy care spaces as the population continues to age and care needs intensify across the senior population. Ontario notably has the fewest seniors’ care spaces relative to the size of the senior population, particularly for heavy care units (3.0 spaces per 1,000 seniors over age 75). A long waitlist for LTC and few spaces for seniors with less intensive – but still significant – care needs suggest a need to expand the number of spaces available for seniors across the care continuum. Notably, British Columbia has the highest vacancy rate for heavy care spaces, despite having relatively few spaces (14.4 per 1,000 seniors over 75). It also has the highest rent among provinces for heavy care spaces ($6,726/month) and the largest increase in rent between standard care and heavy care spaces (Figure 2).

Quebec has more than three times the amount of seniors’ housing spaces in comparison to other provinces, relative to the size of the senior population. It also has the lowest median rent for both standard and heavy care spaces by a large margin. Median rent for a standard care space ($1,873/month) is about half the cost of other provinces, and a heavy care space in Quebec ($3,566/month) costs less than a standard care space in Ontario ($3,845/month).8Quebec having triple the supply but similar vacancy rates to other provinces suggests that lower prices are a result of a significantly higher supply of seniors’ care spaces. 

Demand is also likely to be higher in Quebec due to policies that indirectly support private seniors’ residences and LTC through medical expense and home care tax credits.

Home Care

Home care covers a broad range of services, including personal support for ADLs, homemaking services such as housekeeping, laundry services and meal preparation, and can include professional services such as nursing, occupational therapy, or social work. Across Canada, about 6.1 percent of households receive home care services and 2.8 percent of households have unmet home care needs (Table 1). Unmet need is highest in British Columbia and Ontario, and lowest in Quebec and Atlantic Canada. Notably Quebec and Atlantic Canada also have the highest proportion of households receiving home care.

In Ontario, publicly covered services are generally tailored to an individual’s needs and delivered in their residence (a home in the community or retirement home), following an assessment by a case manager or health professional. Services are delivered by third-party agencies that can operate on a non-profit or for-profit basis. In Quebec, seniors can access discounted home help through the Financial Assistance Program for Domestic Health Services program. After approval, seniors receive a discounted hourly rate for various home care and support services provided by qualifying domestic help and social economy businesses.9 Many services provided by home care agencies and domestic help businesses can also be purchased directly through the private market. This option gives a completely free choice of services, without the need to qualify for government assistance, but must be paid for out-of-pocket. In BC, home support services can be purchased privately, or can be publicly subsidized, based on eligibility. If publicly subsidized, home care recipients are charged a daily rate for services, based on their income.1010 In Alberta, home care is narrowly defined as providing medical support for people so they can live in their homes. After an eligibility assessment, services are provided under Alberta Health Care Insurance meaning that if a service is not insured, it is not publicly funded.

Over half of home care services are paid from government sources (52.2 percent), and 7.3 percent are covered by insurance. More than a quarter (27 percent) are paid for out of pocket (Gilmour 2018). Government sources are more likely to cover health home care services than support services. In 2015/2016, more than half of nursing care services (54.3 percent) and 42 percent of other healthcare services had a monthly cost (Table 2).

In many cases, seniors receiving home care will also receive help from informal caregivers (for example, family members, neighbors, and adult children). Informal care reduces the direct public costs of supporting a senior to maintain their independence in their home, but it can represent economic deadweight loss if informal caregivers reduce their hours of paid work.11In addition to formal in-home services, there are also seniors’ day-programs to provide care throughout the day, and respite care beds for when informal caregivers might need additional support or if the senior needs additional care for a short period of time.

Assisted Living

Depending on the jurisdiction, “assisted living” services overlap somewhat with home care and retirement home services, but generally target those with higher care needs. 

Formal Home Care Received and Unmet Home Care Needs of Canadian Households, 2021

Assisted living programs are defined differently across the country. In Quebec, “Resources intermediaries” provide housing and access to support services for individuals with minor to moderate loss of autonomy. In British Columbia, Assisted Living provides housing, hospitality, and social and recreational services to adults requiring a supportive environment due to physical and functional health challenges. In Ontario, Assisted Living Services provide support for people with special needs who require services at a greater frequency or intensity than home care, but without the medical monitoring or 24/7 nursing supervision that is provided in long-term care. Services are provided by third-party agencies that operate on a not-for-profit basis. In Alberta, Designated Supportive Living is broken down by levels of service, ranging from 24/7 provision of health and personal care services for those living independently, to providing specialized residential dementia care (AGO 2021).

Assisted living services are generally publicly funded, with limited room and board co-payments when housing is included in services. They are targeted to cover gaps in the continuum of care between independent living options and long-term care, and the services provided can overlap with both to ensure appropriate levels of support are provided and seniors are not prematurely admitted to long-term care.

Inappropriate Care Setting: ALC Patients in Hospitals

Alternate Level of Care patients are people occupying an inpatient bed, but whose needs no longer require acute level care. ALC patients occupy 12.7 to 27.5 percent of beds in acute-care centres across the provinces and represent 15.5 percent of all acute-care bed-days in Canada (excluding Quebec) in 2021-2022 (CIHI 2023). ALC patients are most often admitted to acute care as a result of an injury or illness, but subsequently cannot be discharged home as their clinical condition requires new additional support and/or care services such as home care, transfer to a long-term care facility, or another form of specialized care (rehabilitation, psychiatric or complex). In some cases, ALC patients might be admitted for predominantly social reasons: no acute or rapidly accelerating medical condition is present, but certain circumstances force patients and caregivers to turn to emergency departments (for example, real or perceived failing of social services or lack of adequate community supports) (Durante et al. 2023).

ALC patients represent a complex health system challenge with many contributing factors. Lack of access to preventative and primary care services, or to home care and other social services, can result in patients going to emergency rooms when an alternate level of care would be more appropriate. Similarly, a lack of capacity in home care or long-term care can result in ALC patients remaining in hospitals for extended periods of time. Both scenarios represent an inefficient use of limited (and expensive) hospital resources and constrain capacity to provide acute care. From a financial perspective, each ALC patients represent a cost of $730 to $1,200 per day to Canada’s healthcare systems (Whatley 2020).12

While inefficient spending is concerning, preserving limited acute care bed capacity is necessary to prevent bed shortages and ensure accessibility for Canadians. Canada has fewer hospital beds relative to the size of the population than most OECD countries, and high occupancy rates in acute care beds show that the system is strained. While there is no agreed upon “optimal” occupancy rate, 85 percent is often considered the maximum rate to reduce risks of bed shortages. The average across OECD countries was 69.8 percent in 2021. Canada was one of three countries to have a rate over 85 percent and had the fewest beds per capita in the high-occupancy group (OECD 2023).13If Canada reduced the number of ALC patients and the number of days an ALC patient spends in hospital, it could significantly reduce acute care capacity concerns. A 13 percent reduction in ALC days would be sufficient to bring acute care occupancy down to below the 85 percent occupancy threshold to prevent hospital bed shortages, since ALC patients currently occupy 15.5 percent of capacity.

There are opportunities to reduce ALC patient days, both from within the hospital setting and by improving and expanding community and support services. Increasing the number of seniors’ care spaces, increasing the scope and provision of home care, improving primary care access and ensuring that necessary support services are accessible and affordable for seniors would all alleviate the strain on hospitals by preventing admissions and allowing for more rapid discharge of ALC patients to alternate levels of care. Within hospitals, incentives for physicians, families, and the hospital generally encourage longer than optimal stays. Front-line clinical staff (especially physicians) have strong incentives to avoid conflict and risks resulting from acute-care discharges (Chidwick et al. 2017).14Hospitals in some provinces charge a daily fee to recoup the costs resulting from ALC hospitalizations. The fees are generally equivalent to the daily rates for room and board in LTC, not the full cost of an acute care bed. This means that there is little incentive for seniors or their families to prefer one care setting over the other if a patient is destined for long-term care. The hospital, however, cannot charge patients this fee unless they need continuing or chronic care – destined for more or less permanent institutional care.15Hospitals, therefore, have an incentive to designate ALC patients as chronic and in need of long-term care, so that they can recoup costs. In Quebec, hospitals do not charge fees related to ALC. In that case, seniors and their families have an incentive to prefer hospital care over home care, a retirement home or a long-term care home since these options do have financial costs. Provinces should examine their hospital fee policies related to alternate level care to ensure that clinicians, hospitals, and seniors are not incentivized to provide or receive more advanced healthcare services than are necessary to meet the needs of the patient. Hospitals should also evaluate policies and guidance for clinicians and front-line workers on making discharge decisions to reduce referral to long-term care when it can be avoided.

Addressing the unmet care and housing needs of seniors could significantly reduce the number of ALC patients and their lengths of stay in hospitals. Reducing ALC days and admissions would likely be sufficient to reduce the strain on acute care capacity to levels more comparable to international peers and reduce the risk of bed shortages.

Costs of Providing Seniors’ Care in Different Settings

Different settings and types of service provision, with different public programs and levels of subsidization, make comparison across provinces challenging. In this section, I compare public costs of seniors’ healthcare across the country and provide estimates of the public costs of care provision across different settings in Ontario and Quebec.16

Rather unsurprisingly, per capita health expenditure increases with the age of the population, since older and frailer individuals have increasingly intensive healthcare needs. There is some variability between provinces, with New Brunswick and British Columbia having lower spending per capita on care for seniors. Across the country, more than $1 of every $4 of provincial government healthcare spending goes to caring for people over 75 years of age. From 2010-2020, total provincial and territorial government spending on healthcare for the population over 75 increased by 40.5 percent to $52.77 billion, while total government spending on healthcare increased by 56 percent. In some provinces, increases in seniors’ healthcare spending have been driven by growth of the senior population (ON, NS) (Figure 3). Some provinces have contained these increasing costs by reducing per capita spending on seniors’ healthcare (NB, AB, NFL). In others, both increasing senior populations and increased per capita spending contribute to spending growth (QC, PEI, MB, SK and BC). Only in PEI and BC has spending on seniors’ care kept pace with overall increases in healthcare spending.

Meanwhile, seniors are spending more on their own healthcare and living expenses. In 2019, the average senior household (75+) spent $14,440 on housing and $3,260 on healthcare (Table 2). Healthcare costs have stayed relatively constant in real terms from 2010 to 2019, and increased less than total consumption, though private insurance premiums have increased by 117 percent. Food and shelter costs, however, have become more expensive. Seniors who rent their homes are facing challenges in addition to affordability, with more than half of those in unsubsidized rental units having inadequate, unsuitable, or unaffordable housing (Table 3). As needs increase with age, the cost and availability of options will factor into the lifestyle choices seniors make about where they live.

In Ontario, a senior with high care needs would likely qualify for long-term care or assisted living. If those services aren’t readily available, they might require a stay in hospital as they wait for an assisted living or long-term care bed to become available. Regardless of the care setting, the personal costs are similar.17

From a public finance perspective, however, there are different costs associated with different levels of care. A hospital stay for someone over 80 years of age ranges in cost from $4,306 to $11,361 per episode of care. Long-term care costs the province $5,870.70 per month per patient, and the average cost of assisted living is about $1,494 per month per patient.18Previous analysis has shown that the total cost of care is lower in heavy care retirement spaces than in LTC, and that public costs are significantly lower due to residents paying privately for services in retirement homes (Table 3). Public spending is lower if people receive advanced care services at home, or in retirement homes, than in long-term care. Hospitals are the worst option. They have the highest public cost and are also a limited resource. Every hospital bed occupied by an alternate level care patient (ALC) carries an opportunity cost and makes the bed unavailable for acute or critical care, or surgical rehabilitation and monitoring.

The picture for high needs patients in Quebec is similar to that in Ontario, but with notable distinctions. There are no private costs for a hospital stay in Quebec, and room and board charges for public LTC range from $1,294.50 per month to $2,079.90. Quebec has private LTC homes that cost residents $5,000 to $8,000 per month, depending on level of care need.19The public cost of a hospital stay for a patient over 80 years of age is higher in Quebec than in Ontario ($5,627-$14,488), as is the level of subsidization of public LTC ($5,837.73 – 9,379.60 per month per client, depending on type of room). There are similar public costs associated with a hospital stay or a month in LTC in Quebec, but the need to preserve scarce hospital resources remains, meaning that from a public cost perspective, the preference would be for high needs patients to be in LTC homes. If the senior can afford it, a heavy care bed in a private retirement home or private LTC home is most beneficial, from a public finance perspective. Research has shown that the government pays 79.7 percent of residential care costs and 81.7 percent of nursing home costs, or about $53,500 per user of a residential care facility and $82,400 per user of a long-term care facility. Comparatively, home care is estimated to cost $7,140 to $23,634 per client, depending on level of care need (Clavet et al. 2022).20

For mild to moderate needs, seniors can depend on informal caregivers, public or private homecare services, nursing services, or they can choose to live in retirement homes offering the services they need. In many cases, some combination of services is required. Home care services in Quebec can be heavily discounted depending on the level of assistance qualified for under the “Domestic Help” program. In Ontario, those qualifying for public homecare services don’t have out-of-pocket costs.21 In both provinces, homecare services can also be acquired privately, in which case there is no direct public cost.22 In both provinces, retirement homes are generally privately owned and operated and offer a variety of services across a spectrum of care needs. In Ontario, the average rent for a retirement home is $3,845 per month, representing a less affordable option when compared to average household costs.23 In Quebec, retirement homes represent a slight savings compared to the average senior household’s expenses.24Quebec has many more senior living spaces than Ontario, relative to the size of the population. It also has a much lower vacancy rate. As discussed in detail in the next section, different tax credits in each province provide different levels and types of support which likely affect both the accessibility of different types of support services and the distribution of seniors’ receiving care in each setting.

Tax Credits to Support Seniors’ Care

In addition to publicly provided services and subsidies on home and health care services, there are also tax credits that reduce the cost of support services and equipment for seniors. Quebec makes more expansive use of tax credits to support seniors remaining in their homes as they age than Ontario. People over 70 years of age in Quebec can claim up to 38 percent of eligible expenditures through the refundable tax credit for home support services.25 Services eligible for the tax credit include meal preparation or delivery services, nursing care services, home and personal care services (such as housekeepers, landscapers, or aides to assist with bathing, dressing, feeding etc.). For homeowners, only eligible services can be refunded. For tenants, however, a portion of rent can be considered if it includes eligible home support services. Similarly, retirement home residents can claim the portion of their rent that relates to meal preparation and home care services. The total amount that can be refunded takes into account total income, level of dependence, family structure, and the eligible expenses incurred throughout the year. An independent senior could qualify for a maximum of $7,020 in refundable credits based on the maximum service spending of $19,500. Dependent seniors can be eligible for up to $9,180 in refundable credits. The credit is reduced when family income exceeds $69,040.26

In Ontario, residents over 70 years of age can claim up to $1,500, or 25 percent of eligible expenses up to a maximum of $6,000, through the Ontario Seniors Home Care Tax Credit. Eligible expenses fall into several categories including walking aids, hearing devices, wheelchairs, hospital bed for home use, oxygen, vision, dental, or home nursing care. The maximum tax credit is reduced by five percent of family net income over $35,000, meaning about a quarter of households with a member over the age of 75 will qualify for the maximum credit. Claimable expenses are amounts over 3 percent of net income. The Ontario home care tax credit covers both services and equipment but does not allow for rent deductions, while the Quebec credit is for eligible service expenses only. Notably, the level of support provided by the Ontario tax credit is lower than that in Quebec. It covers a smaller proportion of the population and refunds a significantly lower amount. See Boxe 2 for examples of the difference in refundable tax credits for a senior couple in each province.

The federal government and Quebec also offer tax credits for improving home accessibility. The federal home accessibility tax credit is available to people 65 years of age or older, or those with a disability. Eligible recipients can claim up to $10,000 related to renovations or purchasing equipment that improves the accessibility and safety of the home. The renovations must be of an enduring nature and could include wheelchair ramps, walk-in bathing installations, and support bars. Quebec’s tax credit is similar to the federal credit. The Quebec Independent Living tax credit for seniors covers 20 percent of eligible expenses over $250.

There are also tax credits to support informal caregivers. At the federal level and in Ontario and Quebec, immediate family members can claim a tax credit for providing care for a disabled relative. Quebec also offers a refundable tax credit of 30 percent of total expenses for caregivers paying for respite services that provide a short-term replacement for care and supervision of a disabled relative.27

The tax credits available to help seniors stay in their homes are quite expansive, and generally consider age and household income levels. In some cases, the tax credits have restrictive criteria, such as requiring the person receiving care to have a disability, making them more targeted to the population requiring more intensive and ongoing care. In Quebec, the home support tax credits go a step further than in Ontario by including a portion of rent related to services, making retirement home care partially eligible, and by separating tax credits related to devices and services. The tax credits are also available to different age groups: tax credits for home equipment become available at age 65 under federal and Quebec subsidies and are available to those 70 and older in Ontario. Both Ontario and Quebec have reserved tax credit eligibility for home nursing care and other home care services to those age 70 and over. The timing of the availability of tax credits loosely follows the progression of care needs as people age and is targeted at the population in need of assistance – without requiring medical assessments and case managers to determine eligibility.28

However, there is a significant difference in the level of support provided between Ontario and Quebec. As the examples in Boxes 2 and 3 show, the question of whether a senior lives in an owned home or rented accommodations (including retirement homes) significantly changes the level of tax subsidization received in Quebec, but not Ontario. In either case, seniors are likely to qualify for more refundable tax credits to support independent living in Quebec than in Ontario.

Senior Households and Spending Patterns

Developing public policies to support seniors as they age should be informed by seniors’ preferences and levels of need. Some senior households requiring lifestyle or healthcare services have the financial resources to invest in adapting their homes, or to pay for services. 

Many seniors are homeowners and have the ability to downsize or transition to a retirement home or other rented accommodations using the unlocked equity to pay for their accommodations or supplement publicly provided healthcare and lifestyle support services. A significant number of senior households, however, face affordability challenges and are in inadequate or unsuitable housing. This section provides a brief overview of the household spending patterns of seniors and their housing needs, with the aim of informing policies that best provide targeted support to seniors most in need.

The Household Spending Survey from Statistics Canada provides insights into the number, composition, and spending patterns of households across the country. According to the 2019 survey data, there were about 1,991,750 households with at least one person over the age of 75, representing 13.5 percent of the total.29 Nova Scotia has the highest proportion of households with seniors (15.24 percent) and Alberta has the lowest (10.77 percent). The data show that while the majority of households with seniors are living within their means, senior households with below-median incomes, and those who rent, are more likely to face affordability challenges or have difficulty accessing adequate and suitable housing.

Most seniors live alone or as a couple (42 percent and 35 percent, respectively). The distribution of seniors among housing types is similar to the rest of the population; a majority live in single detached houses (54 percent) and about 3 in 10 live in apartments or condos. The majority of senior households own their home without a mortgage, and seniors are more likely to own a second property than the population average. The majority of households with seniors depend on government transfers as their main source of income (52 percent), followed by other forms of income (27 percent) and employment earnings (17 percent).30In general, 75+ households have lower spending and consumption than the average household and spend a lower proportion of their income.31 Senior households spend less than the average in all categories except healthcare and custodial services (though they still spend less on household operations overall). Examining average income and consumption patterns across provinces shows that the average household with at least one person over the age of 75 can meet its needs and still reserve about 30 percent of income as savings, a similar rate to households overall.

Averages, however, can mask more worrisome spending and consumption patterns at the lower end of the income distribution. Households with below-median income have consumption expenditures that exceed their incomes.32 Shelter and food costs represent about 46 percent of consumption expenditures across lower-income households in general, and 53 percent for lower-income households with seniors. Shelter costs exceed the 30 percent affordability threshold for below-median-income households with seniors.33 It is difficult to determine the level of need from these data alone, since many seniors have significant savings to support their consumption. Lower-income seniors who do not have significant savings would be more likely to face affordability challenges. Ontario has the lowest spending on shelter for lower-income households with seniors ($8,862), and those households have significantly lower shelter costs than the average across lower-income households in the province.34 In Quebec and Alberta, shelter costs exceed 35 percent of consumption expenditure for senior households. In British Columbia, seniors who rent spend 46.1 percent of their income on shelter.

The importance of shelter costs to seniors’ expenditures, particularly below-median income households, warrants further investigation. Statistics Canada’s housing indicators provide further details. Households where the primary maintainer is over the age of 85 generally have higher rates of housing inadequacy, unaffordability, and unsuitability than the average across all households (Table 4). Seniors show higher rates of “core need” housing than the general population (see Box 4 for definitions of housing indicators).

In all major provinces, more than a third of renters are in housing that is inadequate, unsuitable, or unaffordable. There are some challenges related to housing indicators for homeowners. Rates of inadequacy, unsuitability, or unaffordability are generally lower for seniors 75+ than for the overall household average. Those who rent are more likely to face difficulties. Notably, more than a third of senior renters in ON, BC and AB cannot afford to move into more suitable housing.35 Quebec, comparatively, has lower rates of core housing need than the other provinces, suggesting that a higher proportion of households could afford to move to adequate or suitable housing. This implies that Quebec has fewer affordability challenges relative to the other provinces, particularly for renters and seniors, despite similar levels of inadequate, unsuitable, or unaffordable housing.

As seniors age, it becomes more likely that they will downsize housing to unlock equity and/or move to more appropriate housing. Similarly, they might choose to transition to renting accommodations in seniors’ care spaces. Between 2016 and 2021, 36 percent of over-75 households sold their homes (CMHC 2023).36This rate has declined over time, showing that more and more seniors are remaining independent for longer and choosing to remain in their homes as they age. Older seniors are more likely to transition to rented accommodations (including private market rental units, retirement homes and LTC) and are also more likely to require supportive services. Declining rental rates and a higher proportion of seniors owning their homes shows a preference for aging-in-place and shows that many seniors can maintain their independence for longer than seniors in previous cohorts. Most seniors would prefer to age in their homes, but many are concerned that they won’t be able to afford to do so. Some seniors are pooling their resources and investing in shared accommodation and care services (Sylvestre-Williams 2024).

There are also “naturally occurring retirement communities” when the majority of inhabitants of a multi-unit dwelling are seniors, or seniors choose to purchase housing in close proximity to each other. These naturally occurring communities could provide opportunities to improve the efficiency of home and community care services. They also reveal the preferences for housing and support services of seniors with adequate financial resources to be strategic and plan for their desired retirement. This could provide insights for new models of seniors’ care that reduce costs by supporting the independence of lower-wealth seniors and encouraging seniors with means to contribute to the costs of their support services.

Overall, the data on household spending and income show that the average household is able to afford its needs, although spending patterns change with age and require higher healthcare expenditures. In general, 75+ households have lower spending and consumption than the average household.37 Seniors that have below-median incomes, however, are facing affordability challenges similar to other households in the category, particularly with regard to shelter. These insights suggest two important factors to consider in developing seniors’ care and support policies. First, many senior households have sufficient resources to fund some lifestyle support and healthcare services, meaning there could be opportunities to develop markets for seniors’ support services to supplement the under-provision of publicly provided home care. Second, some seniors are facing affordability challenges, meaning targeted support policies that holistically consider housing, support, and healthcare needs could reduce the likelihood that these seniors will prematurely enter long-term care or become ALC patients in hospitals. For the Silo, Rosalie Wynoch /C.D. Howe Institute.

Read the full report here.

References


Clavet, Nicholas-James, Réjean Hébert, Pierre-Carl Michaud, and Julien Navaux. 2022. “The Future of Long-Term Care in Quebec: What Are the Cost Savings from a Realistic Shift toward More Home Care?” Canadian Public Policy 48: 35-50.

Canadian Institute for Health Information. 2017. “Seniors in Transition: Exploring Pathways Across the Care Continuum.” Available at https://www.cihi.ca/en/seniors-in-transition-exploring-pathways-across-the-care-continuum

_____________. 2023. Inpatient Hospitalization, Surgery and Newborn Statistics, 2021-2022. Available at https://www.cihi.ca/en/hospital-stays-in-canada-2021-2022

Canadian Mortgage and Housing Corporation. 2023. Housing Market Insights. https://assets.cmhc-schl.gc.ca/sites/cmhc/professional/housing-markets-data-and-research/market-reports/housing-market-insight/2023/housing-market-insight-canada-m11-en.pdf

Chidwick, Paula, Jill Oliver, Daniel Ball, Christopher Parkes, Terri Lynn Hansen, Francesca Fiumara, Kiki Ferrari et. al. 2017. “Six Change Ideas that Significantly Minimize Alternate Level of Care (ALC) Days in Acute Care Hospitals.” Healthcare Quarterly 20(2): 37-43.

Durante, Stephanie, Ken Fyie, Jennifer Zwicker, and Travis Carpenter. 2023. “Confronting the Alternate Level Care (ALC) Crisis with a Multifaceted Policy Lens.” Briefing Paper. University of Calgary School of Public Policy 16(1). Available at https://journalhosting.ucalgary.ca/index.php/sppp/article/view/76748

Nuernberger, Kim, Steve Atkinson, and Georgina MacDonald. 2018. “Seniors in Transition: Exploring Pathways Across the Care Continuum”. Healthcare Quarterly 21(1): 10-12.

Office of the Auditor General of Ontario (AGO). 2021. Value-for-money audit: assisted living services. December. Available at https://www.auditor.on.ca/en/content/annualreports/arreports/en21/AR_AssistedLiving_en21.pdf

Gilmour, Heather. 2018. Formal home care use in Canada. Statistic Canada. September 19. Available at https://www150.statcan.gc.ca/n1/pub/82-003-x/2018009/article/00001-eng.htm#archived

Organisation for Economic Co-operation and Development (OECD). 2023. Hospital Beds and Occupancy. Health at a Glance 2023: OECD indicators. Available at https://oecd-ilibrary.org/sites/bdd23022-en/index.html?itemId=/content/component/bdd23022-en

Roblin, Blair, Raisa Deber, Kerry Kuluski, and Michelle Pannor Silver. 2019. “Ontario’s Retirement Homes and Long-term Care Homes: A Comparison of Care Services and Funding Regimes.” Canadian Journal on Aging / La Revue canadienne du vieillissement 38(2): 155–167.

Statistics Canada. 2022. Home care use and unmet home care needs in Canada, 2021. Available at https://www150.statcan.gc.ca/n1/daily-quotidien/220826/dq220826a-eng.htm

Statistics Canada. 2019. Survey of Household Spending. public use microfile.

Sylvestre-Williams, R. 2024. Don’t want to end up in a nursing or retirement home? Some seniors are finding creative solutions – on their own terms. Toronto Star. March 18. Available at https://www.thestar.com/business/personal-finance/dont-want-to-end-up-in-a-nursing-or-retirement-home-some-seniors-are-finding/article_1253a964-d26f-11ee-964a-c71e7e78215f.html

Whatley, Shawn. 2020. “Patient Hotels: An Established Transitional Solution to Overcrowding.” The Hill Times. February 3. Available at https://www.hilltimes.com/2020/02/03/ patient-hotels-an-established-transitional-solution-to-overcrowding/233033.

Wyonch, Rosalie. 2021. Ounce of Prevention is Worth a Pound of Cure: Seniors Care in Canada After COVID-19. Commentary. C.D. Howe Institute. Available at https://www.cdhowe.org/public-policy-research/ounce-prevention-worth-pound-cure-seniors-care-after-covid-19

Automation Key To Future Of Work Under Great Reset

LOS ANGELES—Automation is no longer an option, automation is the key to surviving the Great Reset.

In 2021, more than 47 million American workers resigned, an annual record. In Canada numbers are harder to determine since accurate resignation numbers are not readily available. However, Statistics Canada has published the results of a survey pitched towards Canadian workers.
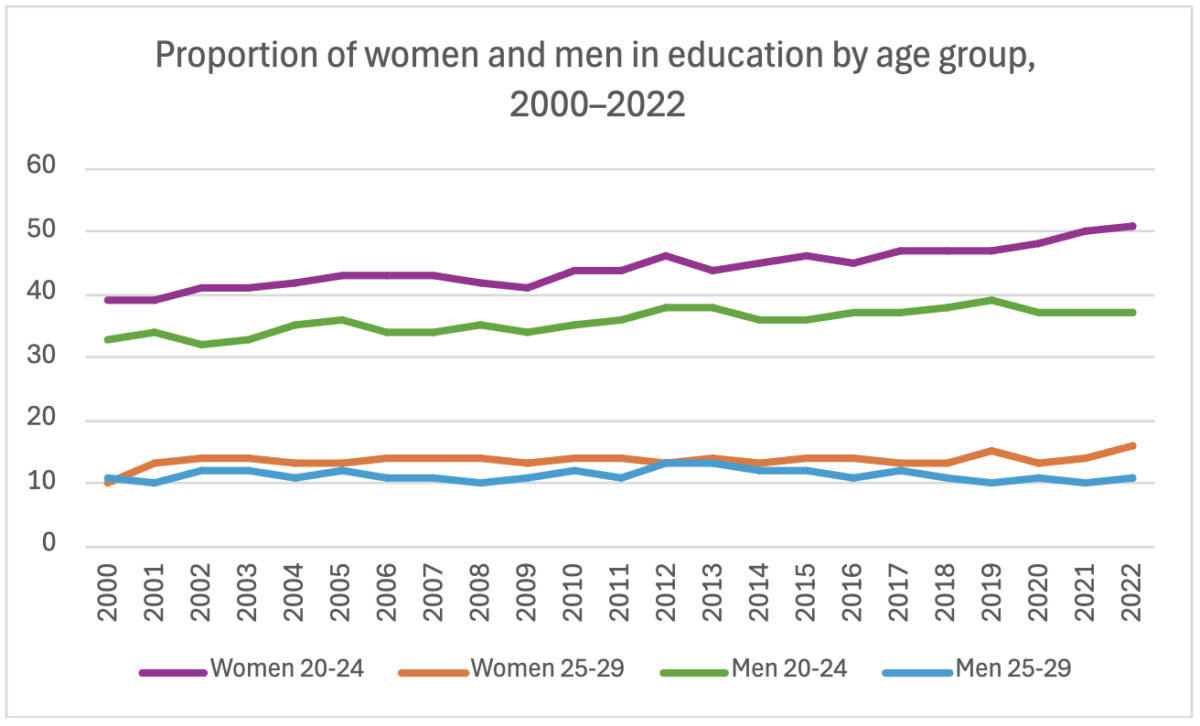
With no sense of the number of people surveyed and the accuracy of the data gathering the results should perhaps be best taken at face value: “In January, respondents were asked whether they were planning to leave their current job, and whether quality of employment considerations were among the reasons for doing so. Fewer than 1 in 10 Canadian workers aged 15 to 69 (7.3%) were planning to leave their current job within the next 12 months, compared with 16.1% in 2016, when respondents to the General Social Survey were asked the same question (not seasonally adjusted). When January 2022 LFS respondents were asked to report their main reason for planning to leave their job, preliminary results show that at least 1 in 5 of those planning to leave (22.2%) reported reasons related to quality of employment, including low pay (15.7%), heavy workload (4.3%) and inability to do their current job from home (2.2%). The trend is continuing. Surveys and data show that 6 in 10 young professionals have changed jobs or plan to and that 4.5 million workers quit their jobs in March.”

Businesses face continuously evolving markets and societal pressures that are transforming the way employees and employers put in exchange with each other to provide value to consumers and clients.

Staffing agencies especially have been under pressure during the pandemic and navigating the Great Reset.

Bilflo automates back-office tasks and helps staffing manage hundreds of contractors and direct hires on a single, simple platform. This allows organizations to conserve time and labor while expanding business operations and profits. The ability to pull in live performance metrics makes it easy for businesses and teams to track their progress on goals. 

“The pandemic was a catalyst for development and expansion, springing from a strong foundation. We spent the past decade developing Bilflo to provide value to clients, especially during a turbulent time,” said Bilflo CEO Barrett Kuethen. “Bilflo was built by staffing industry experts to specifically serve the industry and address the unique operational pains to bridge process gaps.”

As of 2022, Bilflo has an extensive integration roadmap that has started with ATS platforms: Bullhorn and Jobadder along with accounting systems like Quickbooks. The company is expanding with key offerings such as Importing External Time, which will support staffing companies by eliminating redundancy and manual errors from VMS tools and other client time portals. Bilfo’s developers and leadership update the platform responsively to customers to provide optimized results. 

Bilflo is outcome-driven and their case studies with leading companies bring to life their platform and services. Amtec, a 60-year-old staffing company which employs over 1,000 contractors every year, provides talent to industries like health care, IT, aerospace and more. After adopting Bilflo the company reduced back-office labor by 75 percent, doubled capacity and achieved 49 percent annual cost savings. Extension, a 20-year-old full recruitment and staffing company handles up to hundreds of employees per week, and similarly achieved success through Bilflo, saving more than $20,000 usd a year and eliminating 16 hours a week in manual workload.

Bilflo founders held a webinar, in association with Staffing Industry Analysts (SIA), to discuss why and how to automate staffing companies’ back-office processes. Bilflo has already seen success after emerging in the market early this year and has received 3rd party validation from industry leaders like G2.com. Bilflo received recognition as a high performer for 2022 including generally, and for small business, mid-market, “easiest to use,” “easiest to do business with” and for “best support.” G2 features Bilflo reviews and case studies here on back office management, and tech stacks.

Bilflo’s APIs (application program interface) communicate with organizations’ ATS to retrieve information. This eliminates the need for someone to spend hours manually entering data.

Bilflo makes it so that companies can store contract job information such as rates, burdens, timecard types, overtime rules, job site addresses, workers’ comp codes and rates, and more.

In the era of remote work and asynchronous collaboration, companies need systems in place to handle timecard and expense management.

Compliance is more difficult to manage than ever. Bilflo solves these problems by calculating overtime in all states and provinces. Payroll integration and automated invoicing rapidly handle complex payment terms, billing addresses, line item information, and real-time reports.